AI Agents and the Next Shift in Enterprise Productivity

Last updated by Editorial team at bizfactsdaily.com on Friday 30 October 2026
Article Image for AI Agents and the Next Shift in Enterprise Productivity

AI Agents and the Next Shift in Enterprise Productivity

The last decade of enterprise technology has been defined by cloud, mobile, and SaaS. The next decisive shift is likely to come from AI agents: software entities that can understand goals, reason over complex systems, and take actions across tools with minimal human intervention. For executives and operators, the question is no longer whether AI will change productivity, but how quickly agent-based systems will move from pilots to core infrastructure-and what that means for work, control, and competitive advantage. This fresh document looks at what AI agents really are (beyond the hype), how they differ from traditional automation, where enterprises are already deploying them, and the organizational changes needed to translate experimentation into durable productivity gains.

From Chatbots to Agents: What Has Actually Changed?

Most enterprises already know conversational AI in the form of chatbots, copilots, and recommendation engines. AI agents go a step further: instead of just responding, they can plan and act.

Research groups and leading vendors describe agents as systems that combine several capabilities:

Natural-language understanding and generation, typically via large language models (LLMs) such as OpenAI's GPT-4o, Anthropic's Claude, or Google's Gemini.

Tool use and integration, where the model invokes APIs, databases, or enterprise applications to retrieve or update information.

Memory and state, allowing the agent to track context over time, learn user preferences, and manage multi-step workflows.

Reasoning and planning, often using techniques like tool-augmented reasoning or ReAct-style (reasoning + acting) loops.

OpenAI's introduction of GPTs and the GPT Store and Anthropic's tool use and workflow automation features signaled that major model providers now see agents-not standalone models-as the primary interface for enterprise usage. Meanwhile, Microsoft's Copilot Studio, Google's Vertex AI Agents, and AWS Agents for Bedrock are pushing agent frameworks deeper into corporate IT stacks.

The key distinction from earlier RPA and workflow tools is flexibility. Traditional automation is brittle: it follows predefined scripts and fails when inputs deviate. Agents, in theory, can adapt to new instructions, interpret ambiguous requests, and orchestrate multiple tools, making them suited for knowledge work and cross-functional processes rather than just repetitive tasks.

For readers interested in the broader technology context, our coverage of artificial intelligence and technology trends provides additional background.

Why AI Agents Matter for Enterprise Productivity

Productivity in large organizations has long been constrained by coordination costs: handoffs between teams, manual data entry across systems, and the time knowledge workers spend searching, summarizing, and reconciling information. AI agents target these coordination bottlenecks as much as they target direct task execution.

Analysts at McKinsey estimate that current generative AI could automate or significantly accelerate activities that absorb 60-70% of employees' time in some professions, particularly in customer operations, marketing, software engineering, and R&D. Goldman Sachs has suggested generative AI could eventually raise global GDP by 7% over a decade, largely through productivity improvements.

AI agents are a mechanism to capture these gains in practice because they:

Connect to core business systems (ERP, CRM, HRIS, ticketing, data warehouses) via APIs.

Execute multi-step workflows end-to-end, not just single tasks.

Operate continuously, monitoring events and triggering actions without waiting for explicit prompts.

When agents are embedded into business processes, they shift the unit of work from "tasks done by humans with tools" to "outcomes specified by humans, delivered by a mix of agents and humans." That shift, if managed well, can reduce cycle times dramatically and free human capacity for higher-value activities such as strategy, relationship-building, and complex judgment.

For broader macro context on productivity and growth, see our coverage of the global economy and business.

Key Enterprise Use Cases Emerging Now

While many organizations are still in pilot mode, several use cases for AI agents are already maturing. Across markets in North America, Europe, and Asia, similar patterns are emerging.

Customer operations and support

Customer-facing functions are often the first place enterprises experiment with agents because the ROI is measurable and the workflows are structured.

Modern support agents can:

Triage and respond to routine tickets using data from CRM and knowledge bases.

Proactively gather missing information from customers.

Escalate complex cases with a concise summary for human agents.

Trigger actions such as refunds, account changes, or order modifications via integrated systems.

Companies like Zendesk, Salesforce, and Intercom have launched agent-like capabilities that can handle a large share of customer interactions without human involvement. Early adopters report both reduced handle time and higher customer satisfaction when escalation paths and guardrails are carefully designed.

This space also intersects with broader marketing and customer experience strategies, where personalization and speed are increasingly critical differentiators.

Finance, risk, and compliance workflows

In heavily regulated sectors such as banking and insurance, AI agents are emerging as copilots for back-office processes rather than front-line decision-makers-at least for now.

Examples include:

Drafting and validating regulatory reports by pulling data from multiple systems and checking them against supervisory templates.

Monitoring transactions and client communications for potential compliance breaches, highlighting anomalies for human review.

Preparing credit memos or risk assessments by synthesizing internal data, external filings, and market news.

Major financial institutions are working with hyperscalers and fintech vendors to embed agents into risk and compliance stacks, often under close supervision from internal audit and regulators such as the European Central Bank and the U.S. Federal Reserve. For readers focused on this sector, our dedicated banking and investment sections track related developments.

Software engineering and IT operations

Dev-focused AI agents are among the most advanced, thanks to clear feedback loops and structured environments.

Beyond code-generation copilots, emerging patterns include:

Agents that maintain dependencies, open pull requests for security patches, and automatically fix simple test failures.

Incident-response agents that monitor logs, correlate alerts, and propose remediation steps, as seen in tools like GitHub Copilot for Pull Requests and Datadog's AI assistants.

Infrastructure agents that manage cloud resources based on policies, scaling and reconfiguring services in response to demand and cost constraints.

These deployments illustrate a broader trend: agents not only assist individual developers but also orchestrate across systems, gradually reshaping how IT and DevOps teams operate.

Knowledge management and internal "digital employees"

Enterprises are increasingly experimenting with internal agents that behave like digital employees embedded within teams-HR assistants, procurement bots, or research aides.

Such agents can:

Answer policy questions, generate tailored documents, and guide employees through HR or IT processes.

Collect and summarize market intelligence from news, filings, and analyst reports, linking to sources like EDGAR or company investor pages.

Prepare meeting briefs by digesting emails, CRM data, and previous interactions.

While some of these capabilities resemble advanced search, the agent framing is different: the system can be assigned ongoing responsibilities (e.g., "keep this dashboard updated weekly," "flag key competitor moves") and can autonomously decide what information to surface.

How Agents Differ from RPA and Traditional Automation

Many enterprises already have robotic process automation (RPA) platforms and workflow engines in place. The question is whether AI agents simply duplicate that functionality with a new label.

There are three important differences.

First, AI agents are language-native. They can understand unstructured instructions and documents, which means they can operate in domains that were previously too variable for RPA-such as email triage, contract review, or multi-party coordination.

Second, agents can reason across systems rather than just mimic user clicks. Because they interact through APIs and structured tools, they can validate data, cross-check information, and dynamically adjust their plans. This is closer to having a junior analyst than to having a macro recorder.

Third, agents can be multi-modal and multi-channel. With advances in models like GPT-4o's multimodal capabilities, agents can potentially process text, images, and audio, opening possibilities in fields like manufacturing quality control, logistics, and field service-areas that were largely out of reach for traditional back-office automation.

That said, RPA is not going away. In many enterprises, the most pragmatic architecture pairs stable, deterministic RPA components for highly structured tasks with agent layers that handle understanding, decision support, and orchestration. For more on this broader innovation landscape, see our coverage of innovation and global business trends.

The Data and Governance Foundations That Make Agents Work

The promise of AI agents often collides with the reality of enterprise data: fragmented, inconsistent, and locked in legacy systems. Without a strong foundation, agents either hallucinate, access the wrong records, or become too constrained to be useful.

Several technical and governance elements are emerging as prerequisites.

Enterprises are investing in robust data platforms and retrieval systems, such as vector databases and retrieval-augmented generation (RAG), to ensure agents ground their responses in authoritative sources. Vendors like Snowflake, Databricks, and Pinecone are building tooling specifically aimed at agentic and RAG-based applications, while cloud providers offer integrated stacks.

Equally important is granular access control. Agents must respect the same (or stricter) permissions as human users. Techniques like attribute-based access control (ABAC), fine-grained policy engines (e.g., Open Policy Agent), and model-level safety layers are being combined to prevent data leakage and unauthorized actions. NIST and the OECD have both issued AI risk management and responsible AI guidelines that many enterprises use as reference points.

Finally, auditability is non-negotiable. Enterprises increasingly require agents to log not just actions but also the reasoning steps and sources that led to those actions. This is vital for regulated industries and for maintaining trust internally, especially as agents start to make recommendations that affect customers, employees, or financial outcomes.

Organizational Impact: Jobs, Skills, and Operating Models

The introduction of AI agents is not just a technology project; it is an organizational redesign issue. The productivity gains depend on how work is reallocated between humans and agents, and whether employees are empowered-or threatened-by the shift.

Studies from the OECD and the International Labour Organization suggest that generative AI is more likely to transform tasks within jobs than to simply eliminate entire roles in the near term, especially in advanced economies. However, the distributional effects can be uneven, with routine cognitive tasks most exposed.

Enterprises experimenting with agents are adopting several patterns:

Redefining roles around outcomes rather than tasks, with agents handling much of the "glue work" such as documentation, scheduling, and routine analysis.

Establishing "AI product owner" or "agent operations" roles responsible for designing workflows, monitoring performance, and updating prompts and tools.

Rolling out systematic reskilling programs focused on data literacy, prompt engineering, and human oversight of AI systems.

This transformation intersects with broader trends in employment and the future of work. Organizations that treat agents as a way to augment staff and redesign processes, rather than as a blunt cost-cutting tool, tend to see higher adoption and less internal resistance.

Measuring Real Productivity Gains (and Avoiding Illusions)

One of the risks with AI agents is mistaking activity for productivity. A system that generates more emails, more dashboards, or more tickets can look impressive while actually increasing noise and cognitive load.

To avoid this, enterprises are starting to define more rigorous metrics:

Process-level KPIs such as cycle time, error rates, rework levels, and customer satisfaction before and after agent deployment.

Utilization and "time freed" analyses that track how much human time is genuinely reallocated to higher-value work, not just filled with more low-value tasks.

Quality and risk metrics, including the rate of AI-induced incidents or corrections required by human reviewers.

Academic and industry field experiments provide some early evidence. A study published in Science on AI assistance for customer support agents found productivity gains concentrated among less-experienced workers, while top performers saw smaller improvements. This suggests that agents may compress performance differences and raise the floor of productivity, with strategic implications for hiring and training.

Enterprises should also be alert to "automation complacency," where employees over-trust agent outputs. Designing workflows that encourage spot-checking, provide uncertainty estimates, and make it easy to override or correct agents is critical to maintaining quality.

Competitive Dynamics: First Movers vs. Fast Followers

For many leadership teams, the strategic question is timing. Moving too early risks sunk costs on immature tools; moving too late risks ceding a productivity edge to competitors.

Several factors influence the optimal posture:

Data readiness: Firms with cleaner, more integrated data can extract more value from agents and may benefit from being early adopters.

Regulatory environment: Highly regulated sectors may prefer a measured approach, working closely with regulators and industry bodies. The evolving EU AI Act and guidance from U.S. agencies such as the FTC on AI claims and fairness are important reference points.

Talent and culture: Organizations with strong engineering and product cultures are often better positioned to build and iterate agent-based systems in-house, while others may rely more on SaaS vendors and system integrators.

Across markets, a pattern is emerging where global leaders and digital natives aggressively experiment with agents across functions, while more traditional enterprises start with narrow, high-ROI use cases-often in customer service or internal knowledge management-before expanding. Our news and stock markets coverage increasingly highlights how these technology bets are reflected in earnings calls and investor sentiment.

Practical Steps for Enterprises Exploring AI Agents

For organizations still in the early stages, a pragmatic roadmap is taking shape.

First, identify specific workflows where agents can be tested end-to-end, rather than scattering pilots across dozens of micro use cases. Processes with clear metrics, moderate complexity, and manageable risk-such as internal help desks, marketing campaign setup, or invoice triage-are good candidates.

Second, invest in the integration layer. Many failed pilots trace back to agents that are effectively blind or handcuffed because they cannot reliably access the systems needed to act. Building standardized APIs, event streams, and secure tool interfaces is often more important than selecting the "perfect" model.

Third, establish governance early. That includes clear policies on data usage, human-in-the-loop thresholds, incident response, and vendor risk management. Frameworks from bodies like NIST and the OECD can provide structure, but they need to be translated into concrete operational rules.

Finally, communicate transparently with employees. Explaining where agents will be deployed, how performance will be measured, and what new skills will be supported can reduce anxiety and encourage experimentation. Organizations that involve frontline teams in designing and refining agents often discover the most impactful use cases.

Where the Next Shift Is Likely to Come From

Thanks for spending a little time going deeper. The most interesting subjects often reveal more when given the attention they deserve. The current wave of AI agents is still early. Many systems remain brittle, and genuine autonomy is limited by both technical and governance constraints. Yet even in this formative stage, enterprises are beginning to see meaningful gains in speed, consistency, and scalability across key workflows.

Over the next few years, several trends are likely to define the next shift in enterprise productivity:

More powerful, cost-efficient models enabling agents to run continuously on large numbers of tasks.

Deeper integration of agents into core business platforms-from ERP and CRM to industry-specific systems-rather than as standalone pilots.

A clearer division of labor between humans and agents, with job designs, incentives, and training adapted accordingly.

Regulatory and industry standards that codify acceptable uses, safety practices, and accountability structures.

For business leaders, the central question is no longer whether agents will reshape work, but how to harness them in a way that amplifies human capability, respects risk, and builds durable competitive advantage. Those that treat AI agents as a strategic layer in their operating model-not just a set of tools-are likely to be the ones that convert technological possibility into real, measurable productivity gains.
How Circular Business Models Create New Revenue Streams

Last updated by Editorial team at bizfactsdaily.com on Thursday 29 October 2026
Article Image for How Circular Business Models Create New Revenue Streams

How Circular Business Models Create New Revenue Streams

Circular business models are shifting from sustainability buzzword to revenue strategy. As pressure grows from regulators, investors, and customers to reduce waste and emissions, companies are discovering that "closing the loop" can also open up new income sources, improve margins, and deepen customer relationships. Join as we look at how circular models actually generate money, which sectors are moving fastest, and what practical playbooks are emerging for businesses that want to turn environmental responsibility into commercial advantage.

From Linear to Circular: Why the Revenue Logic Changes

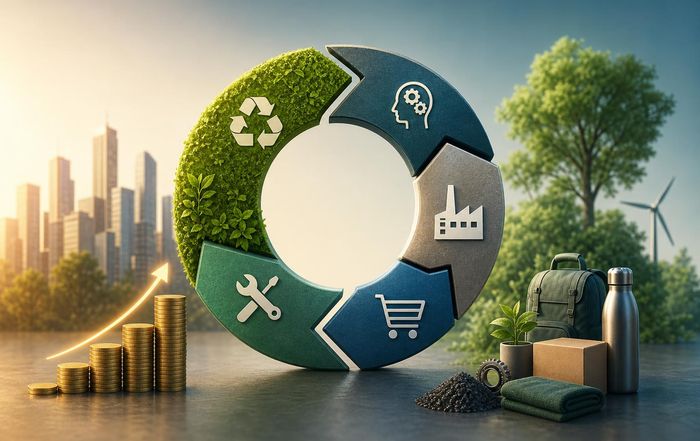
The traditional "take-make-waste" model is built around selling as many new units as possible, as frequently as possible. Revenue depends on volume and replacement cycles. In a circular model, value is designed to circulate for longer through reuse, repair, remanufacturing, and recycling, often supported by digital tools and service-based contracts.

The Ellen MacArthur Foundation defines the circular economy as one that is "regenerative by design," keeping products, components, and materials at their highest value for as long as possible. That shift changes the revenue logic: instead of a single sale followed by disposal, circular models create multiple monetization points over a product's life. In many industries, this also aligns with regulatory trends such as the EU's Circular Economy Action Plan and emerging "right to repair" rules in the US and Europe, which are pushing businesses to design for durability, reparability, and material recovery.

For readers focused on broader business and sustainability trends, this is not just an environmental story. It is about how new circular strategies intersect with innovation, investment, and regulation to reshape competitive advantage.

Key Circular Revenue Models Emerging Across Industries

Circularity is not one model but a family of approaches. Several archetypes have become common across sectors, each with distinct revenue mechanics and risk profiles.

Product-as-a-Service (PaaS) and "X-as-a-Service"

Instead of selling ownership, companies retain ownership and sell outcomes or access. Revenue typically comes from recurring subscription or usage fees, with the provider responsible for maintenance, upgrades, and end-of-life management.

Examples include:

Lighting-as-a-service: Philips (now Signify) pioneered models where it installs and maintains LED systems while customers pay a monthly fee for light output rather than buying fixtures outright. This creates long-term, predictable revenue and incentivizes the company to design durable, energy-efficient products that are easy to refurbish.

Equipment leasing and pay-per-use: Industrial players like Rolls-Royce with its "Power by the Hour" for aircraft engines, or Kaeser Kompressoren with compressed air as a service, charge based on uptime or usage, aligning incentives for reliability and efficient maintenance.

This model can improve margins because assets generate revenue multiple times, backed by data-driven maintenance and high residual value. However, it also requires capital to keep assets on the balance sheet and robust asset-management capabilities. For companies exploring service-based offerings, this intersects strongly with technology and IoT innovation, as sensors and connectivity are often central to making PaaS viable.

Take-Back, Trade-In, and Buy-Back Programs

Many consumer brands now offer trade-in or buy-back schemes, creating new revenue from used products while keeping materials in circulation.

Apple's trade-in program collects old devices, which are either refurbished and resold or disassembled with robots like "Daisy" to recover high-value materials. Refurbished devices are sold at premium margins because acquisition costs are relatively low.

Apparel companies such as Patagonia and The North Face run branded resale programs, selling used gear through their own channels. By controlling the secondary market, they capture value that would otherwise go to third-party resale platforms.

These programs generate revenue in several ways: resale of refurbished products, sale of recovered parts into repair networks, and material recovery for remanufacturing. They can also stimulate demand for new products when customers use trade-in credit, boosting primary sales while building loyalty.

Refurbishment, Remanufacturing, and Certified Pre-Owned

Refurbished and remanufactured products are increasingly mainstream, particularly in electronics, automotive, and industrial equipment.

The International Resource Panel has highlighted remanufacturing as a key strategy for reducing resource use while maintaining economic output, with remanufactured products often costing 30-50% less to produce than new equivalents while selling at a smaller discount to customers.

In automotive, certified pre-owned (CPO) programs by brands such as BMW, Toyota, and Mercedes-Benz generate high-margin revenue from used vehicles that undergo rigorous inspection and refurbishment. CPO cars typically sell at a premium to regular used vehicles, while still undercutting new models.

For business customers, remanufactured industrial components can offer lower total cost of ownership with warranties similar to new parts. For manufacturers, remanufacturing creates additional revenue without the full material and energy cost of new production, while also reducing exposure to raw material price volatility.

Sharing, Rental, and Access Platforms

The rise of digital platforms has enabled models where assets are shared among multiple users, increasing utilization and creating new fee-based revenue streams.

In mobility, car-sharing services (e.g., Zipcar, Share Now) and micromobility platforms (e-scooters and bikes) monetize short-term access. While some early players struggled with profitability, more recent models are focusing on fleet durability, repairability, and local operations efficiency, aligning more closely with circular principles.

Tool libraries and equipment rental services, from global firms like United Rentals to local cooperatives, generate revenue by renting tools and machinery many times over their lifespan, spreading embodied carbon and material use across multiple customers.

For companies with underutilized assets-vehicles, machinery, office space-platforms that enable secure sharing can unlock new income while reducing the need for additional production. However, profitability depends heavily on utilization rates, maintenance costs, and local regulatory conditions.

Materials Recovery and Industrial Symbiosis

Some of the most powerful circular revenue opportunities emerge at the material and ecosystem level, rather than at the individual product level.

Industrial symbiosis projects, such as the long-running example in Kalundborg, Denmark, connect multiple companies so that the by-product of one becomes the input for another. Waste heat, steam, gypsum, and other materials are sold between partners, turning waste management costs into revenue streams.

Companies specializing in advanced recycling, such as Umicore in metals recovery or Eastman in molecular recycling of plastics, generate revenue by processing waste streams into high-purity materials. As regulatory pressure grows on producers to manage end-of-life impacts-through extended producer responsibility (EPR) schemes, for example-demand for such services is increasing.

In many jurisdictions, policies like the EU's Waste Framework Directive and battery regulations are pushing manufacturers to design for recyclability and to finance collection and treatment. This regulatory backdrop is creating new business opportunities for recyclers, logistics providers, and data platforms that track material flows.

Where the Money Comes From: Revenue Levers in Circular Models

Across these models, several common revenue levers appear. Understanding them helps companies design circular strategies with a realistic business case rather than relying on broad sustainability narratives.

First, there is lifetime value expansion. When a company stays involved with a product over its full life-through maintenance, upgrades, trade-in, or resale-it can capture revenue multiple times from the same physical asset. A laptop might generate income as a new sale, a service contract, a refurbished sale, and finally as recovered materials. Each step builds on the sunk design and production cost.

Second, circular models enable new customer segments and price points. Refurbished or remanufactured products can open up value-conscious segments that might not buy new, particularly in emerging markets or among younger consumers. Certified pre-owned programs, for example, attract customers who want brand quality at a lower price, with the brand capturing margin that would otherwise go to independent dealers.

Third, there is recurring and predictable revenue. PaaS and subscription models transform lumpy one-off sales into ongoing fee streams. This can improve cash flow stability and valuation multiples, but it also requires careful risk management around asset performance and customer churn. Digital monitoring and predictive maintenance, often powered by AI and IoT, are increasingly central to making these models financially viable.

Fourth, circularity can unlock cost savings that effectively act like revenue. Lower material input needs, reduced waste disposal fees, and more efficient use of energy and water can significantly improve margins. A McKinsey & Company analysis of the circular economy in Europe estimated potential net material cost savings of up to hundreds of billions of euros annually if circular principles are widely adopted. While these savings show up on the cost side, they expand the economic space for competitive pricing, investment, or profit.

Finally, circular strategies can generate licensing and data monetization opportunities. Companies that develop proprietary remanufacturing processes, tracking technologies, or circular design methods may license them to others. Digital platforms that manage product passports or material traceability-an area gaining traction as the EU develops a Digital Product Passport framework-can monetize access to data, analytics, and compliance services.

Sector Snapshots: Where Circular Revenues Are Growing Fastest

Different industries are moving at different speeds, shaped by regulation, customer expectations, and asset economics. Several sectors stand out as proving grounds for circular revenue models.

Consumer Electronics and IT

Electronics are a natural fit for circularity because devices are high value, resource intensive, and often replaced before the end of their technical life. Trade-in, refurbishment, and certified pre-owned programs are now mainstream among leading smartphone and laptop brands.

Companies such as Apple, Samsung, and Dell have built sizable businesses around refurbished devices and components. Enterprise IT providers like HPE and Cisco run asset recovery and remanufacturing programs that generate revenue from used equipment while helping clients meet sustainability and data-security requirements.

Policy is accelerating this trend. The EU's Ecodesign for Sustainable Products Regulation aims to ensure products are more durable, repairable, and recyclable, while "right to repair" rules in Europe and several US states are making parts and documentation more accessible. This regulatory push is increasing the economic attractiveness of repair, refurbishment, and spare-parts businesses.

For readers tracking technology and innovation, this sector illustrates how design, software updates, and reverse logistics combine to create recurring revenue from a single device.

Fashion and Textiles

Fashion has been under intense scrutiny for its environmental footprint and waste. In response, brands and platforms are experimenting with resale, rental, repair, and take-back programs.

Resale platforms like ThredUp, Vestiaire Collective, and Vinted have shown that second-hand fashion can be a large, fast-growing market. In parallel, brands such as Patagonia, Levi's, and H&M have launched their own resale initiatives, sometimes in partnership with white-label technology providers. These programs generate commission or margin on pre-owned items and can drive traffic back to primary retail channels.

Clothing rental, from occasion-wear services like Rent the Runway to everyday rental in markets such as China and Europe, is another revenue pathway. While unit economics can be challenging due to logistics and cleaning costs, some operators are refining their models with better garment durability and inventory management.

As extended producer responsibility rules for textiles emerge in regions such as the EU, new revenue opportunities are likely in textile sorting, fiber-to-fiber recycling, and digital product passports that track fiber content and care instructions.

Automotive and Mobility

The automotive sector has long operated with some circular elements-used car markets, parts remanufacturing, and leasing-but electrification and digitalization are pushing new models.

Electric vehicle (EV) batteries are a focal point. Companies like Redwood Materials in the US and Northvolt in Europe are building businesses around collecting and recycling batteries to recover lithium, nickel, cobalt, and other critical materials. As EV volumes rise and regulations such as the EU's Battery Regulation tighten requirements for recycled content and end-of-life management, these services represent a growing revenue pool.

At the same time, subscription and flexible ownership models-from OEMs and startups alike-are blending leasing, maintenance, and upgrade options. Over-the-air software updates, performance unlocks, and feature subscriptions (e.g., advanced driver assistance systems) further extend revenue beyond the initial vehicle sale.

For mobility providers and automakers, circular design (durable components, modular interiors, easily replaceable batteries) supports higher utilization, lower lifetime costs, and more predictable revenue from fleets and services.

Industrial and B2B Equipment

In industrial markets, circular models are often less visible to consumers but can be highly material to earnings.

Manufacturers of heavy machinery, compressors, medical equipment, and other capital goods are expanding service and remanufacturing offerings. For example, Caterpillar has a long-standing remanufacturing business (Cat Reman) that restores used components to like-new condition, selling them at a discount with full warranty. This business captures value from core returns, stabilizes demand for new parts, and helps customers reduce costs.

Performance-based service contracts-where providers are paid for uptime, output, or efficiency-create recurring revenue and incentivize robust, repairable design. Digital twins and predictive maintenance, often using AI analytics, help optimize these contracts and reduce downtime, linking circularity closely with artificial intelligence applications in industry.

Enablers: Technology, Data, and Ecosystem Partnerships

Turning circular ambitions into revenue requires more than a new marketing message. It depends on technology, data, and collaboration across value chains.

Digital technologies are central. IoT sensors, connectivity, and cloud platforms enable real-time monitoring of asset condition and usage, making PaaS and pay-per-use models manageable at scale. Data on performance and failure modes feeds back into design, improving durability and ease of repair. Product lifecycle management (PLM) systems and enterprise software increasingly integrate circular metrics, helping companies track assets and materials.

Traceability and transparency are also crucial. Regulators, investors, and customers increasingly expect companies to prove claims about recycled content, ethical sourcing, and end-of-life outcomes. Blockchain-based solutions, digital product passports, and standardized reporting frameworks-such as those discussed by the World Economic Forum in its circularity and traceability initiatives-are emerging to support this.

Ecosystem partnerships matter because no single company can close the loop alone. Brands are collaborating with logistics providers, recyclers, repair networks, and digital platforms to manage returns, refurbishment, and material recovery. Industry alliances and cross-sector initiatives are helping define standards, invest in shared infrastructure, and develop new business models.

For readers interested in global business dynamics, these partnerships highlight how circularity is reshaping supply chains and creating new roles for intermediaries, from specialized refurbishers to data-driven materials marketplaces.

Risks, Trade-Offs, and Common Pitfalls

Circular models are not automatically profitable or risk-free. Companies that rush in without a grounded business case can face financial and reputational challenges.

One key risk is capital intensity and balance-sheet exposure. PaaS and leasing models require companies to own assets longer, tying up capital and increasing exposure to residual value risk if technology changes quickly or demand shifts. Careful scenario planning, modular design, and secondary markets for used assets are essential to mitigate these risks.

Another challenge is operational complexity. Managing reverse logistics, refurbishment, and quality control at scale can be demanding. Without robust processes and data, costs can erode margins. Many early experiments in fast-fashion rental or low-cost electronics refurbishment struggled because logistics, repair, and customer service costs were underestimated.

There is also the danger of greenwashing. As circularity becomes a marketing theme, some companies highlight minor recycling initiatives or token take-back schemes without meaningful impact on design, business models, or revenue. Regulators are responding: the EU is advancing rules against misleading environmental claims, and competition authorities in several countries have scrutinized sustainability advertising. Overstating circular achievements can backfire, damaging trust with consumers and investors.

Finally, circular strategies must navigate regulatory and market uncertainty. Policy frameworks are evolving rapidly, from EPR schemes to product standards and trade rules. At the same time, customer acceptance of refurbished, remanufactured, or subscription-based offerings varies by culture and segment. Companies need to test, iterate, and adapt models to local conditions rather than assuming one-size-fits-all.

Practical Steps for Businesses Exploring Circular Revenue

For leaders considering how to move beyond pilots and press releases, several pragmatic steps can help turn circular ideas into viable revenue streams.

First, start with product and portfolio mapping. Identify which products have high residual value, long technical lifespans, or strong secondary markets. These are prime candidates for refurbishment, remanufacturing, or PaaS models. In parallel, assess where waste disposal costs, material price volatility, or regulatory pressure are highest; these pain points often indicate where circular strategies will have the strongest business case.

Second, build a data foundation. Track where products go after sale, failure patterns, and repair histories. This may require new customer engagement, warranties, or digital features (such as connected devices that report usage). Data is essential to price service contracts, forecast residual values, and design logistics for returns.

Third, experiment with focused pilots rather than wholesale transformation. A trade-in program for a single product line, a remanufactured offering for a particular component, or a PaaS contract with a limited set of customers can test assumptions and refine operations. Success in one segment can then be scaled or adapted elsewhere.

Fourth, invest in design for circularity. Modularity, standardized parts, accessible fasteners, and durable materials can dramatically reduce refurbishment and repair costs, improving the economics of circular models. Cross-functional collaboration between design, engineering, procurement, and service teams is crucial.

Finally, communicate clearly and credibly. Customers need to understand the value proposition of refurbished products, subscriptions, or take-back schemes-not only in environmental terms but in reliability, convenience, and cost. Transparent warranties, performance guarantees, and clear messaging help build trust.

Individuals interested in the broader business and economy context may also watch how investors integrate circularity into ESG analysis and capital allocation, shaping which companies can access financing for these transitions.

Why Circular Revenue Models Matter for Competitive Strategy

Circular business models are often framed as a response to environmental pressure. They are that-but they are also becoming a strategic response to structural shifts in the global economy: resource constraints, regulatory tightening, digitalization, and changing customer expectations.

Companies that successfully embed circularity into their revenue models can reduce dependency on volatile raw material markets, differentiate offerings, and create more resilient, service-oriented income streams. Those that delay may find themselves locked into linear cost structures and exposed to rising compliance and disposal costs.

For business leaders, investors, and people following global economic trends, the key question is no longer whether circular models will matter, but where in each value chain they will create the most sustainable revenue. The organizations that answer that question early-and back it with operational capability-are likely to shape the next wave of profitable, low-carbon growth.

How Digital Identity Could Transform Modern Banking

Last updated by Editorial team at bizfactsdaily.com on Wednesday 28 October 2026
Article Image for How Digital Identity Could Transform Modern Banking

How Digital Identity Could Transform Modern Banking

Digital identity has quietly become one of the most important battlegrounds in modern finance. As banks face rising fraud, tightening regulation, and customers who expect "one-tap" everything, the way individuals and businesses prove who they are is no longer a back-office concern. It is now central to competitiveness, cost structure, and even financial inclusion. This clever article looks at how digital identity is reshaping banking, what models are emerging globally, and what that could mean for customers, regulators, and financial institutions over the next decade.

What "Digital Identity" Really Means in a Banking Context

In banking, digital identity is more than a username and password. It is the set of verified attributes-legal name, date of birth, national ID, biometric data, phone number, device, behavioral patterns-linked to a person or organization and managed so that they can securely access financial services online.

Regulators increasingly expect banks to use risk-based, data-rich digital profiles rather than static documents. Frameworks such as the Financial Action Task Force (FATF) recommendations explicitly recognize digital identity systems as acceptable tools for customer due diligence and anti-money laundering (AML) controls, provided they meet reliability and independence standards. This shift is pushing banks to treat identity as a dynamic, continuously updated asset rather than a one-time onboarding event.

Digital identity also spans multiple layers: proofing (initial verification), authentication (logging in or approving a transaction), authorization (what a user can do), and ongoing monitoring (detecting anomalies). The more integrated these layers are, the more powerful the identity system becomes-for security, personalization, and compliance. For readers interested in how this interacts with broader financial regulation and macro trends, our coverage of banking and economy developments provides additional context.

Why Banks Are Betting on Digital Identity

For banks, the economic logic behind digital identity is compelling. Traditional onboarding with in-branch visits, manual document checks, and wet signatures is expensive and slow. McKinsey has estimated that robust digital ID systems can reduce customer onboarding costs by up to 90% in some markets while improving fraud detection and customer satisfaction. At the same time, cybercrime and identity theft are surging, putting pressure on outdated password-based systems.

There is also a competitive dimension. Fintechs and big tech companies have raised expectations for frictionless digital experiences. When a user can open a digital wallet in minutes or log in to a service with a biometric scan, a bank that still relies on paper forms and multiple branch visits risks losing market share. Digital identity is increasingly the foundation for the kind of "instant everything" service model that customers now expect in payments, lending, and wealth management. Readers tracking these shifts in financial services can find more on our business and investment pages.

Regulatory pressure is another driver. In the EU, eIDAS (electronic IDentification, Authentication and trust Services) and its upcoming upgrade, often called eIDAS 2.0, are pushing toward a European Digital Identity Wallet that will allow citizens to prove their identity and share attributes across borders. The European Banking Authority has highlighted how such schemes can be used for remote customer onboarding under PSD2 and AML rules. In markets like India, regulators and governments have gone even further, creating public digital identity infrastructure that banks can rely on at scale.

Global Models: From Aadhaar to BankID and Beyond

Different regions are experimenting with different identity architectures, and these models are shaping how banks operate.

In India, the Aadhaar system-managed by the Unique Identification Authority of India (UIDAI)-assigns a 12-digit unique ID linked to biometrics and demographic data for residents. Banks can use Aadhaar-based eKYC (electronic Know Your Customer) to verify customers quickly and at low cost. This has been central to India's "India Stack," enabling rapid growth in digital accounts and payments through systems such as UPI. While Aadhaar has sparked ongoing debates over privacy and surveillance, it remains a powerful example of state-backed digital identity infrastructure transforming financial access.

In the Nordic region, BankID in Norway and Sweden and NemID/MitID in Denmark have become widely adopted national digital identity schemes anchored in the banking sector. According to BankID Norway's own figures, over 90% of the adult population uses BankID to access banking, government services, and private-sector platforms. Here, banks act not only as consumers of digital identity but also as major providers, sharing a common scheme that reduces duplication and creates network effects.

The European Union's evolving European Digital Identity Wallet proposal aims to create interoperable wallets that citizens can use to store and present digital credentials, including those relevant to banking. The European Commission has published details on this initiative, emphasizing user control and selective disclosure of attributes. Banks in Europe are watching closely because they may eventually be required-or strongly incentivized-to accept these wallets for onboarding and transaction authorization.

In North America, the landscape is more fragmented. In the United States, initiatives such as the Better Identity Coalition and the FIDO Alliance's passkey standards are pushing for stronger authentication and digital identity practices, but there is no single national ID system. Instead, banks rely on a mix of credit bureau data, document scanning, biometrics, and device intelligence. Canada is moving faster toward a coordinated framework, with the Digital ID & Authentication Council of Canada (DIACC) promoting standards and public-private collaboration.

These varied models illustrate a critical strategic choice: whether digital identity is primarily government-led, bank-led, or ecosystem-led. Each approach has implications for competition, privacy, cross-border interoperability, and the role of big tech platforms in finance.

From KYC to Continuous Identity: Operational Impacts on Banks

The most immediate impact of digital identity on banks is in onboarding and KYC/AML processes. Instead of a one-time, paper-based check, banks are moving toward continuous identity assurance, in which multiple signals are combined over time to assess whether a user is who they claim to be and whether their behavior is legitimate.

This involves technologies such as document recognition, liveness detection for selfies, biometric authentication, and device fingerprinting, often provided by specialist vendors. Firms like Onfido, Jumio, and IDnow have grown quickly by offering AI-driven identity verification services that banks can integrate into their digital channels. Regulators, including the U.S. Financial Crimes Enforcement Network (FinCEN) and the UK Financial Conduct Authority (FCA), have issued guidance on how remote identity verification can be used while maintaining compliance.

Operationally, this can reduce manual review work, lower error rates, and cut onboarding times from days to minutes. It also enables more dynamic risk scoring. For example, if a customer suddenly logs in from a new device in a high-risk jurisdiction and attempts a large transfer, the bank can trigger step-up authentication or additional checks. These capabilities depend on a rich digital identity graph rather than static records of past documents.

However, the transition is not trivial. Banks must integrate new identity technologies with legacy core systems, retrain staff, and manage complex vendor ecosystems. For institutions that operate across multiple jurisdictions, aligning digital identity processes with different regulatory expectations adds further complexity. This is particularly relevant for global banks active in stock markets and cross-border investment services, where inconsistent identity standards can become a significant operational burden.

Customer Experience: Frictionless, But Not Friction-Free

From a customer perspective, the most visible impact of digital identity is a smoother experience. Opening an account by scanning an ID document, taking a selfie, and linking a phone number has become common in many markets. Biometric logins on mobile apps, QR-code approvals, and push-notification confirmations are now standard for digital-first banks and increasingly for incumbents.

Yet the challenge is to remove unnecessary friction without compromising security. Overly aggressive security prompts can drive users away or encourage risky workarounds, while too little friction can invite fraud. Behavioral biometrics-analyzing how a user types, swipes, or holds a device-are emerging as a way to add "invisible" security. Companies like BioCatch and BehavioSec provide such capabilities, and banks use them to flag unusual patterns that may indicate bots, account takeovers, or social engineering.

Banks also have to manage customer trust. High-profile data breaches and misuse of personal data by technology platforms have made users wary of how their identity information is handled. Regulations such as the EU's General Data Protection Regulation (GDPR) and California's Consumer Privacy Act (CCPA) set legal boundaries for data use, but banks that want to leverage identity data for personalization must go further, building transparent consent flows and clear value propositions.

In practice, the banks that succeed are often those that explain why they collect certain data, give customers control over sharing, and demonstrate tangible benefits-such as faster loan decisions, more relevant offers, or reduced fraud. This intersects with broader trends in technology and marketing, where data-driven personalization is increasingly expected but closely scrutinized.

Security and Fraud: Strengthening Defenses, Shifting Attack Surfaces

Digital identity can dramatically strengthen security in banking, but it also changes where and how attackers operate. Passwords are widely recognized as a weak link; phishing, credential stuffing, and password reuse continue to drive account compromises. Standards from the FIDO Alliance and the move toward passkeys and WebAuthn-based authentication are pushing banks to adopt phishing-resistant methods anchored in devices and biometrics.

Multi-factor authentication (MFA) has become a regulatory requirement in many jurisdictions. Under the EU's Revised Payment Services Directive (PSD2), "strong customer authentication" (SCA) mandates at least two factors from categories such as knowledge, possession, and inherence. Digital identity systems that combine device binding, biometrics, and cryptographic keys can meet these requirements while minimizing user friction.

However, as front-end authentication becomes stronger, criminals increasingly target the identity proofing and account recovery stages, as well as social engineering. Deepfake audio and video, synthetic identities (constructed from real and fake data), and sophisticated "pig butchering" scams are testing banks' defenses. The U.S. Federal Trade Commission (FTC) and other regulators have warned about rising losses from such schemes, particularly in crypto-related fraud and investment scams.

Banks must therefore treat digital identity as a full lifecycle challenge. That includes robust onboarding, continuous behavioral monitoring, secure recovery processes, and strong controls around employees who can override automated systems. Artificial intelligence is a double-edged sword here: it powers more accurate anomaly detection but also enables more convincing fraud attempts. Our artificial intelligence coverage explores how financial institutions are grappling with this tension.

Financial Inclusion: Opportunity and Risk

One of the most compelling arguments for digital identity in banking is its potential to expand financial inclusion. The World Bank's ID4D initiative estimates that around 850 million people globally lack any form of official ID. Without recognized identity, opening a bank account, receiving government payments, or accessing credit is often impossible. Digital ID systems can lower barriers by enabling remote onboarding and leveraging alternative data such as mobile usage or transaction history.

India's Aadhaar-linked bank accounts and mobile money ecosystems in parts of Africa illustrate how identity and payments infrastructure can work together to bring millions into the formal financial system. In Kenya, for example, the mobile money platform M-Pesa and national ID systems have combined to support widespread digital financial services, with research by the MIT Sloan School of Management suggesting positive impacts on poverty reduction.

Yet there are also risks. Poorly designed digital ID schemes can exclude those without smartphones, stable connectivity, or certain documents. Biometric systems can struggle with manual laborers, the elderly, or individuals with disabilities, leading to false rejections. Centralized databases can become tools for surveillance or discrimination if not governed properly. Civil society organizations, including Privacy International and the Electronic Frontier Foundation, have raised concerns about mission creep and the potential misuse of identity data.

For banks, this creates both an ethical and strategic challenge: how to leverage digital identity to reach underserved populations-such as migrants, gig workers, and informal entrepreneurs-while avoiding new forms of exclusion or reputational damage. In many emerging markets, partnerships between banks, mobile operators, and fintechs are exploring hybrid models that combine formal IDs with alternative data and community-based verification.

The Rise of Reusable and Self-Sovereign Identity

A major trend in digital identity is the move away from siloed, institution-specific credentials toward reusable identity and, in some cases, self-sovereign identity (SSI). In a reusable model, a customer verifies their identity once with a trusted provider and then reuses that credential across multiple services, including banks. This can reduce onboarding friction and duplication of KYC checks, cutting costs for banks and improving user experience.

In Europe, initiatives like bank-based identity schemes and the planned EU Digital Identity Wallet aim to make such reuse mainstream. In Canada, the Pan-Canadian Trust Framework promoted by DIACC envisions a similar ecosystem of trusted identity providers. For banks, participating in these schemes can create new roles: they may act as identity issuers, verifiers, or both.

Self-sovereign identity takes this further by using decentralized identifiers (DIDs) and verifiable credentials, often built on blockchain or distributed ledger technologies. Projects such as the Trust over IP Foundation and various pilots under the Linux Foundation umbrella explore how individuals can hold their credentials in digital wallets and selectively disclose attributes (for example, proving they are over 18 or resident in a country) without revealing full documents.

Some banks and financial consortia are experimenting with SSI for corporate onboarding, trade finance, and cross-border KYC. The Global Legal Entity Identifier Foundation (GLEIF) is working on verifiable LEIs that could be embedded in digital credentials for organizations. While SSI remains early-stage, it aligns with broader concerns about privacy, data minimization, and user control-issues that regulators increasingly emphasize.

At the same time, banks must be realistic about adoption timelines. Large-scale shifts to SSI require not only technical standards but also governance frameworks, liability rules, and integration with existing AML and sanctions screening processes. For now, most banks are likely to operate in a hybrid world where traditional identity systems, reusable credentials, and emerging SSI tools coexist.

Regulatory and Governance Challenges

Digital identity in banking sits at the intersection of financial regulation, data protection, cybersecurity, and sometimes national security. This makes governance complex. Regulators must balance innovation and competition with consumer protection and systemic risk concerns.

In the EU, eIDAS, GDPR, PSD2, and the upcoming EU AI Act all touch aspects of identity in financial services, from how biometric data is processed to how automated decision-making is explained. In the United States, sectoral rules such as the Gramm-Leach-Bliley Act (GLBA), state privacy laws, and guidance from agencies like FinCEN, the Office of the Comptroller of the Currency (OCC), and the Federal Reserve shape banks' identity practices. Internationally, the Basel Committee on Banking Supervision and FATF set high-level expectations that influence national rules.

For banks, a key challenge is ensuring that digital identity initiatives comply with these overlapping frameworks while remaining flexible enough to adapt as rules evolve. Governance must cover not only internal processes but also third-party vendors, data-sharing arrangements, and participation in shared identity schemes. Boards and senior management are increasingly expected to understand these issues, not treat them as purely technical or operational.

Strong governance also requires meaningful oversight of AI and machine-learning models used in identity verification and fraud detection. Regulators are asking how bias is mitigated, how explainability is ensured, and how adverse impacts are monitored-particularly where identity systems might affect access to essential financial services. These questions intersect with broader debates about responsible AI, a topic we cover frequently in our innovation and global sections.

Strategic Choices for Banks: Build, Buy, or Federate?

As digital identity becomes more central, banks face strategic decisions about how deeply to invest and what role they want to play in the broader ecosystem.

Some large institutions are building substantial in-house capabilities, viewing identity as a core differentiator and a potential revenue stream. They may offer identity-as-a-service to other firms or play a leading role in national schemes, as Nordic banks have done with BankID. This approach demands significant investment in technology, risk management, and regulatory engagement but can create powerful network effects and data advantages.

Others prefer to buy or partner, integrating third-party identity verification, authentication, and fraud tools. This can accelerate time-to-market and reduce upfront costs but may limit differentiation and increase dependency on vendors. Banks that serve high-risk sectors or operate in many jurisdictions often adopt a modular strategy, combining multiple providers and internal tools to tailor risk controls.

Federated models-where multiple banks and other institutions share a common identity infrastructure or trust framework-are also gaining traction. These can reduce duplication, spread costs, and create more consistent customer experiences. However, they require robust governance, clear liability rules, and mechanisms to manage competition concerns. In some markets, regulators or industry associations act as conveners to help align incentives.

Ultimately, the strategic question is not whether to engage with digital identity, but how. For many banks, identity will be as fundamental as payments or credit in determining their future role in the financial system.

How Banking Could Look Once Digital Identity Matures

If current trends continue, banking in a mature digital identity environment could look very different from today.

Customers might hold a digital wallet containing verified credentials from governments, banks, employers, and other trusted issuers. Opening a new account, applying for a mortgage, or onboarding to an investment platform could involve simply presenting a subset of these credentials, with consent-based data sharing and minimal manual input. KYC and AML checks could be largely automated, with cross-institutional reuse of verified data reducing duplication and errors.

Authentication would rely primarily on device-bound cryptographic keys and biometrics, making phishing far less effective. Behavioral analytics and continuous risk scoring would run in the background, stepping up security only when needed. Identity and access management would extend beyond customers to encompass employees, partners, and APIs in a unified framework, supporting open banking and embedded finance.

For underserved individuals and small businesses, more inclusive identity frameworks could enable tailored financial products based on a richer understanding of their circumstances, including alternative data sources. At the same time, strong privacy protections and data minimization would be essential to prevent overreach and maintain trust.

Banks that adapt successfully could see lower fraud losses, reduced compliance costs, and new revenue opportunities in identity services. Those that lag may find themselves disintermediated by more agile competitors, including technology platforms that control identity touchpoints even if they do not hold deposits directly.

The Bottom Line

Digital identity is not a side project for IT or compliance teams; it is becoming a strategic pillar of modern banking. It affects how customers are acquired, how risks are managed, how regulators are satisfied, and how new business models-such as open banking and embedded finance-are realized.

The transformation is still uneven, with different regions and institutions moving at different speeds and along different paths. But the direction of travel is clear: identity will be more digital, more reusable, more data-rich, and more tightly integrated into the fabric of financial services.

For banks, and technology providers, the challenge now is to shape this transformation in ways that enhance security, foster innovation, and expand access-without sacrificing privacy, fairness, or resilience. How that balance is struck will go a long way toward defining the future of global finance.

Innovation Portfolios for Companies Facing Capital Constraints

Last updated by Editorial team at bizfactsdaily.com on Tuesday 27 October 2026
Article Image for Innovation Portfolios for Companies Facing Capital Constraints

Innovation Portfolios for Companies Facing Capital Constraints

When capital is tight, innovation is often the first line item to be cut-and that is usually a mistake. The challenge for leadership teams is not whether to innovate, but how to structure an innovation portfolio that fits hard financial limits while still positioning the business for future growth.

This article explores how companies under capital constraints can design, prioritize, and manage innovation portfolios with discipline, using tools that investors and product leaders already understand. The focus is practical: how to choose the right mix of projects, how to fund them, and how to kill them when they no longer deserve scarce cash.

Why constrained capital changes the innovation game

In periods of easy money, companies can afford broad exploration: many parallel bets, long payback periods, and tolerance for fuzzy business cases. When interest rates rise, credit tightens, or internal cash flows weaken, the economics of innovation change quickly.

Higher discount rates make distant cash flows less valuable, which means long-horizon R&D projects look worse in net present value (NPV) terms. Boards and CFOs demand shorter payback, lower risk, and clearer line-of-sight to profitability. According to McKinsey and other strategy firms, a large share of corporate value still comes from innovation, but the hurdle rate for new projects increases when capital costs rise. At the same time, competitors may also be pulling back, creating openings for disciplined innovators.

For many firms, this environment coincides with other pressures: digital transformation, AI adoption, sustainability regulation, and shifting labor markets. Leaders cannot simply stop innovating; they must reconfigure their innovation portfolios with the same rigor they apply to their investment and stock market decisions.

What an innovation portfolio is-and why it matters more when money is scarce

An innovation portfolio is the set of initiatives a company funds to create new value: new products, services, business models, processes, or technologies. Like a financial portfolio, it should be diversified across risk, time horizon, and strategic purpose. In practice, this means not only having different types of projects, but also managing them as a system rather than as isolated bets.

Under capital constraints, a portfolio approach matters for several reasons:

It forces explicit trade-offs: every dollar in one initiative is a dollar not available for another.

It makes risk visible: leadership can see if the company is overexposed to long-shot "moonshots" or, conversely, stuck in incrementalism.

It aligns innovation with strategy: initiatives can be mapped to clear strategic themes rather than scattered pet projects.

It enables staged funding: projects can be financed in tranches tied to evidence, not in large, upfront lump sums.

Frameworks such as the three horizons model popularized by McKinsey and the ambidextrous organization concept from Michael Tushman and Charles O'Reilly provide useful starting points, but they need to be adapted to financial realities. The core idea is to balance exploitation (improving the core business) and exploration (creating the next business) in a way that fits the firm's capital position and risk appetite.

Diagnosing your current innovation portfolio

Before redesigning anything, companies should map the portfolio they already have. Many discover that their "innovation budget" is heavily skewed toward incremental improvements in existing products or IT, with only a small fraction dedicated to genuinely new offerings or business models.

A practical diagnostic typically looks at:

Type of innovation: product, service, process, business model, or enabling technology (for example, artificial intelligence or advanced analytics).

Customer and market focus: existing customers vs. new segments; existing geographies vs. new regions.

Time horizon: near-term (0-2 years), mid-term (2-5 years), long-term (5+ years).

Risk and uncertainty: technical risk, market risk, regulatory risk, and execution risk.

Capital intensity: upfront capex, working capital needs, and ongoing opex.

Simple visual tools-such as bubble charts plotting risk vs. value, or horizon maps-help executives see concentration and gaps. Strategyzer and similar innovation tool providers offer public examples of such portfolio maps, while academic work from institutions like MIT Sloan and Harvard Business School provides conceptual grounding on portfolio balance.

When capital is constrained, this diagnostic should also highlight:

Projects with large cash outlays in the next 12-24 months.

Initiatives consuming scarce specialist talent.

Projects with weak or outdated business cases.

"Zombie" initiatives that continue due to sunk-cost bias or internal politics.

This view sets the stage for rebalancing.

Principles for innovation under capital constraints

Companies with limited capital cannot simply copy the innovation playbooks of cash-rich tech giants. Instead, they need a set of principles that reflect financial discipline.

First, they must be explicit about strategic themes: a small number of clearly articulated domains where the company will innovate. These might include AI-enabled services, low-carbon solutions, or new digital distribution channels. The themes should tie directly to the firm's broader business and economy context and be anchored in rigorous market insight rather than internal enthusiasm alone.

Second, they should adopt evidence-based funding. Rather than approving large budgets based on multi-year business plans, they can fund projects in stages tied to learning milestones-customer validation, technical feasibility, regulatory clarification, or early revenue. This approach draws on practices from venture capital and lean startup methodologies, as described by Steve Blank, Eric Ries, and many corporate innovation case studies published by outlets such as Harvard Business Review.

Third, they should treat cash and critical talent as portfolio-level constraints. The question is not "Is this project attractive?" but "Is this project more attractive than the alternatives for our next dollar and our next hour of scarce engineering or commercial talent?" This mindset mirrors capital allocation decisions in private equity and can be supported by tools like stage-gates and internal hurdle rates.

Finally, they should embrace option thinking. Many innovation initiatives are real options: relatively small investments that create the right, but not the obligation, to invest more later. Real options theory, discussed extensively in finance literature and by organizations such as the CFA Institute, provides a useful lens for valuing flexibility in uncertain environments.

Designing a constrained innovation portfolio: three core buckets

While every company's context is different, most constrained portfolios can be organized into three broad buckets. The mix among them should reflect strategic priorities and financial capacity.

1. Core enhancements with fast payback

These are low-to-moderate risk projects that improve existing offerings, processes, or customer experiences. They typically have:

Short payback periods (often under two years).

Clear impact on revenue, margin, or cost.

Modest capital requirements relative to other initiatives.

Examples include pricing and packaging changes, digital self-service tools, targeted automation using technology or AI, or incremental product upgrades. Research from Bain & Company and industry benchmarks often show that such initiatives can deliver attractive returns with limited risk, especially when they leverage existing channels and customers.

Under capital constraints, many firms overweight this bucket, which is understandable but risky if it becomes the only focus. A healthy portfolio allocates a meaningful share of innovation spend here to generate near-term cash that can help fund more exploratory bets.

2. Adjacent growth plays

Adjacent innovations extend the core into new segments, channels, or offerings without entirely reinventing the business model. They are riskier and often require more investment, but they typically build on existing capabilities and brand strength.

Examples might include:

Entering a new customer segment with a tailored version of an existing product.

Expanding into a nearby geography using current distribution partners.

Creating a subscription or "as-a-service" variant of a historically one-off product, a move seen in many industrial and software businesses.

Layering AI-based features or data services on top of existing offerings.

Research by Bain and others suggests that adjacency moves are a major source of growth for many established firms, but also a common source of failed acquisitions and overreach. Under capital constraints, adjacency bets should be tightly scoped, with clear go/no-go criteria and structured experiments to validate demand.

3. Selective transformational bets

Transformational innovations create or enter entirely new markets or business models. They carry higher uncertainty and usually longer payback, but they are often critical for long-term relevance-especially in industries facing disruption from AI, climate policy, or shifting consumer behavior.

Examples include:

Building a new digital platform or marketplace in a traditionally asset-heavy industry.

Developing a radically new product category based on emerging technologies.

Pivoting from product sales to full lifecycle solutions or outcome-based contracts.

In a constrained environment, few companies can afford many such bets. However, eliminating them entirely can leave the firm exposed to disruption and unable to participate in emerging profit pools. The key is to limit the number of transformational initiatives, manage them as options with small initial investments, and use partnerships, corporate venture capital, or ecosystem plays to share risk.

Organizations like the World Economic Forum and OECD regularly publish analyses on innovation and productivity that underscore the importance of such forward-looking investments, even for mature industries and emerging markets.

Prioritization: ranking initiatives when you cannot fund them all

Once the portfolio is structured conceptually, leadership must decide which specific projects to fund, scale, pause, or kill. Under capital constraints, prioritization needs to be more than a scoring exercise; it must be a transparent decision process that withstands scrutiny from boards, investors, and operational leaders.

Many firms use a scoring model incorporating:

Strategic fit (alignment with themes and competitive positioning).

Financial attractiveness (NPV, IRR, payback, or contribution margin).

Probability of success (technical and market).

Capital intensity and timing of cash outflows.

Capability fit (leverage of existing strengths vs. need to build new ones).

Option value (what the project enables if successful).

However, scoring tools can be gamed or oversimplify uncertainty. To counter this, companies can:

Run scenario analyses for major initiatives, especially where macro economy or regulatory outcomes are uncertain.

Use decision-making frameworks like those described by Gary Klein and others, including pre-mortems to surface hidden risks.

Involve cross-functional panels (finance, operations, sales, technology, risk) to challenge assumptions.

Regulators and bodies such as the IFRS Foundation and FASB provide guidance on capitalizing vs. expensing R&D, which can also influence prioritization by affecting reported earnings and leverage ratios. Finance and innovation leaders should collaborate to ensure portfolio decisions are consistent with accounting and disclosure requirements.

Funding models that stretch scarce capital

When internal capital is limited, companies can rethink how innovation is funded, both internally and externally.

Internally, staged funding is critical. Projects can be broken into phases-discovery, validation, build, and scale-with each phase receiving a defined budget and explicit evidence thresholds for progressing. This approach is consistent with lean startup and agile methodologies, and is widely discussed in resources from Lean Enterprise Institute and Scaled Agile.

Externally, companies can access additional capital or reduce upfront investment through:

Partnerships and joint ventures: sharing development costs and risks with suppliers, customers, or peers. For example, automotive and energy companies often co-invest in charging infrastructure or battery technology.

Corporate venture capital (CVC): investing minority stakes in startups that explore strategic domains. CVC units, tracked by organizations like Global Corporate Venturing, allow firms to access innovation without bearing full development risk.

Public funding and incentives: many governments offer grants, tax credits, or low-cost financing for R&D, green technologies, or digital transformation. Databases from the European Commission, U.S. Small Business Administration, and national innovation agencies can help identify such programs.

Customer-funded development: co-creating solutions with key customers who are willing to pre-pay, sign long-term contracts, or share development costs. Enterprise software and industrial B2B markets frequently use this model.

Smaller and mid-sized companies, which often face tighter bank lending conditions, may also explore alternative financing such as revenue-based financing or specialized venture debt, though these instruments come with their own risk profiles and covenant structures.

Using AI and data to make innovation portfolios smarter

Data and AI can materially improve innovation portfolio decisions if applied thoughtfully. Rather than treating innovation as a purely qualitative art, companies can use analytics to inform where and how they invest.

Examples include:

Analyzing historical project performance to identify patterns in success and failure-by market, sponsor, technology, or business model.

Using market and competitive data from sources such as CB Insights, PitchBook, or Crunchbase to understand where external capital is flowing and which technologies are gaining traction.

Applying machine learning to customer data to identify unmet needs, churn drivers, or adoption patterns that inform innovation themes.

Scenario modeling of macroeconomic variables-interest rates, commodity prices, regulatory changes-to stress-test major initiatives.

At the same time, AI is itself a domain of innovation. Many firms are building AI-enabled products, automating internal processes, or experimenting with generative AI for marketing, customer service, and operations. Resources from organizations such as OECD.AI and NIST provide guidance on trustworthy AI, while regulators in the EU, US, and elsewhere are developing frameworks that may affect AI-related innovation. Companies must factor regulatory and ethical considerations into their AI-heavy innovation portfolios.

Readers interested in the intersection of AI and business innovation can also explore broader coverage on artificial intelligence and technology more generally.

Governance: who owns the constrained portfolio?

Even the best-designed portfolio will fail without clear governance. Under capital constraints, governance must achieve two aims: protect scarce resources and ensure that strategic opportunities are not suffocated by short-term pressures.

Many firms adopt a tiered governance model:

A top-level capital allocation committee, often including the CEO, CFO, and business unit heads, sets overall innovation investment levels and approves the largest or riskiest bets.

A central innovation or strategy team manages the portfolio view, supports business units in designing initiatives, and ensures consistency in evaluation criteria.

Business units or product lines sponsor specific projects, provide domain expertise, and are accountable for execution.

To avoid innovation being starved during annual budget cycles, some companies allocate a fixed percentage of revenue or operating profit to innovation, with internal rules about how much must go to each portfolio bucket. Others create ring-fenced funds for strategic themes, insulated from quarterly fluctuations in performance. Research and case studies from INSEAD, London Business School, and other institutions showcase examples of such governance structures across industries.

Transparency is essential. Regular portfolio reviews-quarterly or semi-annual-allow leadership to reallocate resources based on new information, kill underperforming initiatives, and double down on promising ones. These reviews should be informed by clear metrics, including both financial and non-financial indicators.

Metrics that fit a constrained, staged approach

Traditional financial metrics like NPV and IRR remain important but are often insufficient for early-stage innovation, where uncertainty is high and data are limited. Under capital constraints, companies need metrics that:

Reflect learning progress, not just financial outcomes.

Capture capital efficiency and time-to-evidence.

Enable comparisons across diverse types of initiatives.

Useful measures include:

Cost per validated learning milestone: how much capital is required to reach critical proof points (for example, a working prototype, signed pilot customers, regulatory approval).

Time to first revenue or pilot: how quickly the initiative generates external validation.

Capital intensity per unit of expected value: a ratio of required investment to potential value under realistic scenarios.

Portfolio kill rate: the percentage of projects stopped at each stage, which should be non-trivial if the process is rigorous.

Balance metrics: share of spend by bucket (core, adjacent, transformational) and by time horizon.

Organizations like OECD and the World Bank publish comparative innovation and R&D statistics that can help firms benchmark their overall innovation intensity against peers and economies, although internal portfolio metrics will always be more granular.

Culture: sustaining innovation when budgets are tight

Capital constraints often lead to risk aversion and defensive behavior. Yet innovation portfolios depend on people willing to experiment, challenge assumptions, and pursue uncertain opportunities. Culture and incentives must therefore be tuned to support disciplined risk-taking rather than blind conservatism.

Key cultural elements include:

Psychological safety: teams must be able to surface bad news early without fear of punishment. This is critical for killing projects quickly and reallocating capital.

Recognition for smart terminations: leaders who shut down doomed initiatives based on evidence should be recognized, not penalized for "failure."

Cross-functional collaboration: innovation projects need input from finance, operations, marketing, technology, and compliance, particularly in regulated industries like banking or crypto.

Capability building: training in customer discovery, experimentation, financial modeling, and data literacy can dramatically improve the quality of innovation proposals.

Reports from organizations such as OECD, World Economic Forum, and leading business schools consistently highlight culture and leadership as decisive factors in innovation performance, often more so than raw R&D spend.

How different types of companies can adapt these ideas

The specifics of innovation portfolios under capital constraints vary across company types and regions.

Large incumbents in mature industries often have significant cash but face internal capital rationing, legacy systems, and regulatory obligations. For them, portfolio work often focuses on pruning, simplification, and shifting spend from low-value maintenance to higher-return initiatives.

Mid-sized companies may be more agile but vulnerable to credit tightening and volatile cash flows. They often benefit most from partnerships, customer-funded development, and targeted use of public incentives.

Startups and scale-ups live with capital constraints as a constant reality. Their portfolios are narrower, but the same principles-option thinking, staged funding, and evidence-based decisions-apply. Founders can draw on ecosystems, accelerators, and investor networks, topics explored further in coverage on founders and global business trends.

Public-sector and non-profit organizations face budget rules and political scrutiny but still need innovation to deliver services and policy outcomes. Many adopt portfolio approaches inspired by private-sector tools, adapted to public value metrics rather than profit. Across all these contexts, the central question remains: how to convert limited capital into the greatest possible strategic and financial impact through a coherent set of innovation bets.

Bringing it together: a disciplined path forward

For companies facing capital constraints, innovation is not a luxury to be deferred until conditions improve. It is a core mechanism for navigating uncertainty, defending margins, and creating future growth options. The difference in a constrained environment is that innovation must be managed with the same rigor as any other investment portfolio.

That means:

Mapping the current set of initiatives and making trade-offs explicit.

Structuring the portfolio across core, adjacent, and transformational buckets with realistic proportions.

Prioritizing based on strategic fit, capital efficiency, and option value-not just enthusiasm.

Using staged, evidence-based funding and diversified financing models to stretch scarce resources.

Leveraging AI and data to inform decisions while managing associated risks.

Putting governance, metrics, and culture in place to support ongoing reallocation rather than one-off budget exercises.

In practice, this is less about discovering a novel framework and more about integrating strategy, finance, and innovation into one conversation. Organizations that do this well can turn capital constraints into a forcing function for focus and discipline-emerging leaner, sharper, and better positioned for the next cycle of growth.

Digital Asset Risk Management Moves Into the Mainstream

Last updated by Editorial team at bizfactsdaily.com on Monday 26 October 2026
Article Image for Digital Asset Risk Management Moves Into the Mainstream

Digital Asset Risk Management Moves Into the Mainstream

For more than a decade, digital assets were treated as a speculative side bet. Risk controls were often an afterthought, and many traditional institutions stayed away entirely. That posture is no longer tenable. With regulators tightening rules, institutional capital flowing in, and tokenization expanding beyond cryptocurrencies into securities, funds, and real-world assets, digital asset risk management is rapidly becoming a core discipline for global finance. This shift is changing how banks, asset managers, corporates, and even technology firms think about governance, controls, and capital allocation. It is also forcing convergence between traditional risk frameworks and the new technical realities of blockchains, smart contracts, and decentralized finance (DeFi).

Why digital asset risk can no longer be sidelined

Several structural shifts have pushed digital asset risk into the mainstream of corporate and financial governance.

Institutional adoption has accelerated. Large asset managers such as BlackRock and Fidelity have launched spot bitcoin exchange-traded products in the United States, following similar moves in Europe and elsewhere. According to BlackRock's own filings, the firm explicitly frames bitcoin exposure within its broader risk and compliance apparatus, a sign that crypto is being absorbed into established investment processes rather than treated as a separate experiment. At the same time, major banks are building custody, trading, or tokenization platforms, with JPMorgan's Onyx and HSBC's Orion among the most visible examples.

Regulation has also intensified. The Financial Stability Board (FSB) released a global framework for crypto-asset regulation in 2023, calling for same-activity, same-risk, same-regulation treatment and urging national regulators to close gaps that could threaten financial stability. The Bank for International Settlements (BIS) and the Basel Committee on Banking Supervision have issued guidance on how banks should treat crypto exposures for capital purposes, including strict limits on high-risk assets like unbacked cryptocurrencies. These moves signal that regulators expect robust risk management comparable to other asset classes, not experimental or lightly governed activity.

At the same time, the industry has been shaped by high-profile failures. The collapse of FTX, Celsius, and Voyager, as well as the implosion of the Terra/Luna ecosystem, exposed deep weaknesses in governance, conflicts of interest, and basic controls. Reports by the U.S. Commodity Futures Trading Commission (CFTC) and Securities and Exchange Commission (SEC) on these failures highlight deficiencies in segregation of client assets, risk concentration, and transparency that would be unacceptable in traditional finance. For institutional investors, these episodes turned digital asset risk from a theoretical concern into a board-level issue.

Finally, the scope of "digital assets" is expanding. It now encompasses cryptocurrencies, stablecoins, tokenized securities, central bank digital currencies (CBDCs), non-fungible tokens (NFTs), and tokenized real-world assets such as funds, bonds, and even trade finance instruments. As tokenization spreads across capital markets and payments infrastructure, risk management cannot be confined to a crypto-native niche; it has to be integrated into enterprise-wide frameworks.

For readers following developments in crypto, banking, and investment sectors, these forces collectively explain why digital asset risk is now treated as a mainstream discipline rather than a specialist hobby.

The evolving risk landscape: beyond price volatility

In the early years, digital asset risk was often equated with price volatility. Bitcoin's dramatic boom-and-bust cycles, and similar patterns in other tokens, dominated headlines. Volatility remains central, but the risk landscape has become far more multidimensional as institutions engage with a wider set of use cases and technologies.

Market risk still matters, especially where leverage is involved or where digital assets are used as collateral. The 2022-2023 deleveraging cycle in crypto markets, which contributed to the collapse of several lenders and trading firms, illustrated how quickly liquidity can evaporate in thinly regulated venues. For institutions, this raises questions about market depth, slippage, and the reliability of price feeds. The International Organization of Securities Commissions (IOSCO) has highlighted market integrity and manipulation risks as central concerns for crypto-asset trading platforms.

Counterparty and credit risk take on new forms as well. In centralized venues, the risk is familiar: the exchange or lender may fail, misuse client assets, or misrepresent its financial health. In DeFi, counterparty risk is partly replaced by smart contract and protocol risk, but users may still be exposed to governance attacks, oracle manipulation, or hidden dependencies on centralized components. The failure of the algorithmic stablecoin TerraUSD in 2022, documented by the U.S. Federal Reserve, showed how design flaws and reflexive dynamics can turn a seemingly stable instrument into a source of systemic contagion within the crypto ecosystem.

Operational and technology risks are especially prominent in digital assets. Private key management, wallet security, and secure interaction with smart contracts introduce challenges that do not exist in traditional securities custody. High-profile hacks of exchanges and protocols-such as the Ronin Network exploit attributed by the FBI to North Korean actors-have resulted in billions of dollars in losses. Institutions must evaluate whether to use cold, warm, or hot storage, how to structure multi-signature or threshold key schemes, and how to segregate client assets on-chain.

Legal, regulatory, and compliance risks are also intensifying. Questions about whether a token is a security, a commodity, or a payment instrument affect everything from disclosure obligations to licensing requirements. Enforcement actions by the SEC, CFTC, European Securities and Markets Authority (ESMA), and other regulators underscore that misclassifying or mishandling digital assets can lead to significant penalties. The European Union's Markets in Crypto-Assets Regulation (MiCA), which began phasing in from 2024, sets out detailed requirements for issuers and service providers, including capital, governance, and disclosure obligations. Firms active in Europe must now align their risk frameworks with MiCA's provisions, not just internal policies.

Finally, there are financial crime and sanctions risks. Digital assets are subject to anti-money laundering (AML) and counter-terrorist financing (CTF) rules, with bodies such as the Financial Action Task Force (FATF) issuing guidance on virtual asset service providers and the "travel rule". The use of mixers, privacy coins, and cross-chain bridges can complicate compliance. At the same time, blockchain analytics tools provide unprecedented transparency if used correctly. Institutions must balance privacy, regulatory expectations, and operational practicality when designing controls.

For businesses following broader global and economy trends, the message is clear: digital asset risk is not a single dimension but a complex matrix spanning markets, technology, law, and compliance.

How traditional risk frameworks are being adapted

As digital assets move into the mainstream, institutions are not starting from zero. Instead, they are adapting established enterprise risk management (ERM) frameworks, internal control systems, and regulatory capital models to incorporate the specifics of blockchain-based instruments.

On the governance side, many banks and asset managers are assigning digital asset oversight to existing risk committees rather than creating separate silos. This approach aligns with the FSB's call for integrated supervision and helps avoid fragmented or inconsistent treatment. Boards are asking for clear risk appetites, limits, and escalation paths for digital asset exposures, just as they do for derivatives, credit portfolios, or complex securitizations. In some cases, firms are appointing dedicated digital asset risk officers who report into the broader risk function.

Market and credit risk teams are extending their models to cover on-chain data and crypto-specific market structure. Value-at-risk (VaR) calculations now incorporate digital asset price histories, correlations with other markets, and liquidity measures such as order-book depth and on-chain transfer volumes. Stress testing scenarios, guided by regulators like the European Central Bank (ECB) and Bank of England, increasingly include shocks to crypto markets or stablecoin de-pegging events, reflecting concerns about potential spillovers into broader financial stability.

Operational risk frameworks are being updated to reflect new failure modes. This includes mapping critical processes such as key generation, transaction signing, wallet recovery, and interaction with smart contracts; identifying potential points of human error, system failure, or insider abuse; and designing controls such as segregation of duties, access management, and automated monitoring. Many institutions are using established standards like ISO/IEC 27001 for information security and NIST cybersecurity frameworks as baselines, layering digital asset-specific procedures on top.

Compliance and legal risk functions are developing taxonomies to classify digital assets according to their regulatory treatment across jurisdictions. These taxonomies underpin decisions about onboarding clients, listing tokens, or participating in DeFi protocols. For example, a bank may permit exposure to regulated stablecoins issued under MiCA, restrict unregistered security tokens, and prohibit privacy coins that raise heightened AML concerns. This structured approach helps ensure consistent application of policies and reduces the risk of ad hoc decision-making.

Crucially, many institutions are building bridges between their on-chain activities and traditional risk data infrastructure. That can involve integrating blockchain analytics feeds into existing risk dashboards, using oracles to bring off-chain reference data into on-chain smart contracts, or reconciling on-chain positions with internal books and records. Without these connections, digital asset activity remains opaque to central risk functions, undermining the very goal of mainstream integration.

New tools of the trade: from blockchain analytics to smart contract audits

Mainstreaming digital asset risk management has spurred the development and adoption of specialized tools that complement traditional risk systems.

Blockchain analytics platforms such as Chainalysis, TRM Labs, and Elliptic provide transaction monitoring, wallet risk scoring, and sanctions screening based on on-chain behavior. These tools are increasingly used by banks, payment providers, and exchanges to comply with AML/CTF obligations and to investigate suspicious activity. For example, Chainalysis' annual crime reports are frequently cited by regulators and law enforcement agencies to quantify illicit activity trends in crypto markets.

Smart contract auditing has become a standard expectation for DeFi protocols and token issuers. Independent security firms review code to identify vulnerabilities such as re-entrancy attacks, integer overflows, or faulty access controls. While audits do not guarantee safety, they provide a baseline level of assurance and can reveal structural weaknesses before they are exploited. The Ethereum Foundation and security-focused organizations like OpenZeppelin publish guidelines and frameworks that projects and institutions can adopt when engaging with smart contracts.

Custody technology has also matured. Institutional-grade custodians offer segregated wallets, insurance coverage, and integrations with trading venues and lending platforms. Many use hardware security modules (HSMs), multi-party computation (MPC), or other cryptographic techniques to reduce single points of failure in key management. Regulators, including the Office of the Comptroller of the Currency (OCC) in the United States and BaFin in Germany, have issued guidance on digital asset custody that influences how banks and third-party providers design their controls.

On the data side, index providers and market data firms now offer reference rates, indices, and benchmarks for digital assets, often subject to governance standards similar to those applied to traditional benchmarks. This supports more robust valuation, performance attribution, and risk reporting. Some providers also incorporate environmental, social, and governance (ESG) metrics, such as the carbon intensity of proof-of-work mining, which is relevant to investors focused on sustainable finance.

Internal audit and assurance functions are beginning to incorporate digital asset controls into their testing programs. Professional bodies such as the Institute of Internal Auditors (IIA) and ISACA have published guidance on auditing blockchain environments, helping organizations evaluate whether their controls over digital asset operations are designed and operating effectively.

These tools do not replace foundational risk management disciplines; they extend them into a new technological domain. For companies that already have strong technology and innovation capabilities, the challenge is to integrate these solutions into coherent, enterprise-wide architectures rather than deploying them as isolated point products.

Regulatory convergence and its impact on risk practices

Regulatory developments are one of the strongest drivers of mainstream digital asset risk management. Around the world, supervisors are moving from high-level principles and enforcement-driven approaches toward more detailed, prescriptive regimes.

In the European Union, MiCA establishes licensing requirements for crypto-asset service providers, conduct-of-business rules, and prudential safeguards such as own-funds obligations and governance expectations. The regulation explicitly requires firms to have sound risk management frameworks, including policies for managing market, liquidity, operational, and legal risks related to crypto-asset services. ESMA and the European Banking Authority (EBA) are issuing technical standards that further specify expectations, including on complaints handling, conflicts of interest, and safeguarding of client assets.

In the banking sector, the Basel Committee's standard on the prudential treatment of crypto-asset exposures introduces a two-group classification. Group 1 covers tokenized traditional assets and certain stablecoins that meet strict criteria, which may be treated similarly to other exposures under existing frameworks. Group 2 covers unbacked crypto assets and high-risk stablecoins, which are subject to conservative capital requirements and exposure limits. This taxonomy forces banks to differentiate between types of digital assets in their risk and capital planning rather than treating all crypto exposure as homogenous.

In the United States, the regulatory landscape remains fragmented, but agencies have signaled clear expectations. The SEC has pursued enforcement actions against exchanges, issuers, and lending platforms, arguing that many tokens are securities and that platforms must register or qualify for exemptions. The Federal Reserve, FDIC, and OCC have issued joint statements warning banks about the safety and soundness risks of certain crypto activities, effectively steering them toward tightly controlled, well-understood use cases such as tokenized deposits or permissioned networks. The Treasury's illicit finance risk assessments on virtual assets emphasize the need for robust AML and sanctions controls.

In Asia and the Middle East, several jurisdictions are positioning themselves as hubs for regulated digital asset activity. Singapore's Monetary Authority (MAS) has introduced a licensing regime under the Payment Services Act, with detailed AML and technology risk requirements. Hong Kong's Securities and Futures Commission (SFC) has created a framework for virtual asset trading platforms, including suitability assessments for retail investors and stringent custody standards. The Dubai Virtual Assets Regulatory Authority (VARA) is building a dedicated regulatory system for virtual assets, aiming to attract international firms while setting clear risk and compliance expectations.

For multinational institutions, this patchwork of rules requires careful jurisdictional mapping and a flexible risk framework that can accommodate differing definitions, licensing categories, and reporting obligations. It also reinforces the trend toward treating digital assets as part of mainstream regulatory compliance rather than as experimental or lightly governed activities.

Readers interested in regulatory-driven shifts in business and stock markets will recognize this pattern: once detailed rules emerge, risk management rapidly becomes a competitive necessity, not just a defensive measure.

Strategic implications for banks, asset managers, and corporates

As digital asset risk management matures, it is reshaping strategic choices across sectors.

For banks, the question is no longer whether to engage with digital assets, but how and on what terms. Many are focusing on tokenization of traditional instruments, on-chain collateral management, and digital custody for institutional clients. These activities can generate fee income and support capital markets businesses, but they require substantial investment in infrastructure, controls, and regulatory engagement. Banks that can demonstrate strong risk management may gain an edge in winning mandates from cautious institutional clients and regulators.

Asset managers face a different calculus. Some are launching dedicated crypto or digital asset funds, while others are integrating tokenized assets into existing strategies. The emergence of spot bitcoin and ether ETFs in multiple jurisdictions has brought crypto exposure into mainstream portfolios. Risk teams must decide how to treat these exposures: as a separate asset class with its own limits, as part of alternatives, or as a component of broader thematic strategies such as digital infrastructure or inflation hedging. They also need to address operational questions about valuation, liquidity management, and counterparty selection.

Corporates are exploring digital assets for treasury management, payments, and supply chain applications. A small number hold crypto on balance sheet, but more are experimenting with tokenized deposits, programmable payments, and on-chain trade finance instruments. For these firms, risk management focuses on treasury policies, accounting treatment, and operational resilience. Standards issued by bodies like the International Financial Reporting Standards (IFRS) Foundation and FASB on accounting for crypto assets influence how CFOs and audit committees view the risk-reward trade-off.

Across all sectors, talent and organizational design are emerging as constraints. Effective digital asset risk management requires a blend of traditional risk expertise and deep technical understanding of blockchains, smart contracts, and cryptography. Many institutions are building cross-functional teams that bring together risk, compliance, technology, and business stakeholders. Training programs, secondments, and partnerships with specialized firms are common strategies to accelerate capability building.

For companies focused on employment trends, this creates a growing demand for professionals who can operate at the intersection of finance, technology, and regulation-risk managers who understand both VaR models and Solidity code, compliance officers comfortable with both FATF guidance and DeFi protocols, and technologists who can translate security concepts into business-relevant risk metrics.

Where digital asset risk management goes from here

As digital asset markets mature and integrate with the broader financial system, risk management will continue to evolve along several dimensions.

First, the boundary between "crypto" and "traditional" finance is likely to blur further. Tokenized versions of familiar instruments-money market funds, government bonds, syndicated loans-will coexist with native digital assets. Risk frameworks will need to focus less on the technology label and more on the underlying economic exposures, legal rights, and governance structures. A tokenized bond issued under robust legal frameworks may pose different risks from an unbacked governance token, even if both live on the same blockchain.

Second, real-time and predictive risk monitoring will become more important. Blockchains generate granular, high-frequency data on positions, flows, and behaviors. As analytics tools improve, institutions will be able to monitor concentration, liquidity, and counterparty risks with much shorter lags than in traditional markets. This could enable more dynamic risk limits, automated margining, and early-warning indicators-but only if data quality, analytics, and governance keep pace.

Third, cross-chain and interoperability risks will rise as assets and applications move across multiple networks. Bridges and interoperability protocols have already been frequent targets for exploits. From a risk perspective, firms will need to assess not only the security of individual chains but also the resilience of the connections between them. This is analogous to how traditional risk managers evaluate both individual institutions and the networks that connect them, such as payment systems and clearinghouses.

Fourth, policy debates will continue around the appropriate level of openness and programmability in financial infrastructure. Central bank digital currencies, regulated stablecoins, and tokenized bank deposits each embody different trade-offs between innovation, control, and risk. Institutions will need to scenario-plan around these policy outcomes, adjusting their strategies and risk frameworks as regulatory and market preferences evolve.

Finally, digital asset risk management will increasingly intersect with broader corporate priorities such as sustainability, data privacy, and operational resilience. Environmental concerns around proof-of-work mining, for example, have already influenced investor attitudes and regulatory scrutiny. As more financial activity moves on-chain, questions about data sovereignty, privacy-preserving technologies, and resilience against cyber and geopolitical shocks will become central to risk discussions.

For businesses and investors tracking important news in digital finance, the overarching trend is clear: digital asset risk management is no longer an optional add-on or a niche specialty. It is becoming an integral part of how institutions design products, allocate capital, engage with customers, and satisfy regulators.

Those that treat it as a strategic capability-not just a compliance burden-are likely to be better positioned as the next phase of digital finance unfolds.

South America's Digital Finance Market Enters a New Phase

Last updated by Editorial team at bizfactsdaily.com on Sunday 25 October 2026
Article Image for South America's Digital Finance Market Enters a New Phase

South America's Digital Finance Market Enters a New Phase

South America's digital finance landscape has moved well beyond the early wave of mobile banking apps and flashy neobank launches. Across the region, regulators, incumbents, fintechs, and Big Tech are now contending with a deeper structural shift: digital finance is becoming embedded in everyday commerce, credit, and even public policy. The questions for businesses and investors are no longer whether digital finance will take off, but which models will dominate, how regulation will evolve, and where the next pockets of growth and risk will emerge.

This article looks at how the market is changing, what is driving the new phase of growth, and what it means for banks, fintech founders, and investors watching the region.

From underbanked to app-first: how the foundation was built

For years, South America was characterized by high levels of financial exclusion, concentrated banking sectors, and relatively low competition. According to the World Bank's Global Findex 2021, Latin America and the Caribbean saw account ownership rise from 55% in 2014 to 73% in 2021, with much of the jump occurring between 2017 and 2021 as digital channels spread and governments pushed digital transfers during the pandemic. Brazil, Colombia, and Argentina saw particularly strong gains as people opened accounts to receive social benefits or stimulus payments via mobile.

This shift created fertile ground for digital-first challengers. Brazilian neobank Nubank, founded in 2013, became a regional bellwether, growing to over 100 million customers across Brazil, Mexico, and Colombia by mid-2024, according to its public filings. Similar models emerged in Argentina (such as Ualá), Colombia (like Daviplata and Nequi), and Chile, focused initially on low-fee cards and simplified current accounts. Smartphone penetration, falling data costs, and widespread frustration with incumbent banking fees and bureaucracy helped these players scale quickly.

Yet the current phase of development is no longer just about adding digital accounts. The region is transitioning from digitizing existing banking products to building new rails, new business models, and more integrated ecosystems that connect payments, credit, savings, and commerce. This is where the market is clearly entering a new stage.

Real-time rails and open finance: Brazil sets the tone

The most visible catalyst for the new phase has been the rapid adoption of real-time payments and open banking frameworks, especially in Brazil. The Central Bank of Brazil (BCB) launched its instant payments system, Pix, in 2020. By mid-2024, Pix handled more than 5 billion transactions per month, according to BCB data, making it one of the most widely used instant payment systems globally. The system allows individuals and businesses to send money 24/7 using simple identifiers like phone numbers or QR codes, often at zero or very low cost.

Pix has reshaped the competitive landscape. It reduced card interchange revenues, pressured traditional banks' fee income, and opened space for new business models in merchant acquiring, small-business payments, and embedded finance. It also created a public, interoperable alternative to private wallets and closed-loop systems, which has implications for Big Tech and incumbent card networks.

At the same time, Brazil's Open Finance initiative-an evolution of open banking-has expanded the scope of data sharing beyond current accounts and credit cards to include insurance, investments, and pensions. Under this framework, customers can consent to share their financial data across institutions through standardized APIs. The BCB and the National Monetary Council publish the rules and technical standards through the official Open Finance Brazil portal.

For digital finance players, this means:

Lower customer acquisition friction, as consumers can port their data and transaction histories to new providers.

New credit scoring models based on richer transactional and behavioral data, potentially expanding access for thin-file or informal-economy workers.

Increased competition on user experience, pricing, and personalization rather than on information asymmetry.

Other South American markets are watching closely. Chile passed a Fintech Law in 2023 that lays the groundwork for open finance and new fintech licensing categories, overseen by the Comisión para el Mercado Financiero (CMF), with technical norms published on the CMF website. Colombia and Peru are developing their own open finance and instant payments frameworks, though they are at earlier stages and face greater institutional and infrastructure constraints.

For readers tracking the broader business and regulatory implications, developments around open banking and digital infrastructure are closely connected to our coverage of banking, innovation, and technology.

Fintech 2.0: from pure-play neobanks to diversified ecosystems

The first wave of South American fintechs focused on single-product beachheads: no-fee credit cards, digital wallets, or SME lending platforms. As competition intensifies and customer acquisition costs rise, many are now evolving into multi-product ecosystems and platform businesses.

Several trends stand out:

First, neobanks are moving up the value chain. Nubank has expanded into personal loans, SME banking, investments, and insurance, partnering with players like Chubb for protection products. Argentina's Ualá has invested in Ualá Bis, a merchant acquiring platform, and acquired a bank license in Mexico to deepen its product range. These moves reflect a shift from growth-at-all-costs to building more diversified revenue streams.

Second, "embedded finance" is taking hold. E-commerce platforms, gig-economy marketplaces, and B2B SaaS providers are increasingly offering financial services directly within their own interfaces, often via partnerships with licensed banks or fintech infrastructure providers. For example, Brazilian e-commerce champion Mercado Libre has grown Mercado Pago into a major payments and credit player, providing wallets, buy-now-pay-later (BNPL), and working-capital loans for merchants across several countries. Its filings with the U.S. Securities and Exchange Commission (SEC) highlight how financial services are becoming central to its business model, not just an add-on.

Third, infrastructure fintechs are gaining prominence. Rather than compete for end customers, these firms provide KYC/AML tools, credit scoring, fraud detection, and payment orchestration to banks and other fintechs. The rise of these B2B providers indicates a maturing ecosystem where specialization and partnerships become more important than building everything in-house. This shift is directly relevant to investors following investment trends in the region.

Finally, traditional banks are responding more proactively. Major incumbents in Brazil, Colombia, and Chile have launched digital-only brands, revamped their mobile apps, and increased partnerships with fintechs. Some are investing in or acquiring startups to accelerate their digital capabilities. The competitive line between "fintech" and "bank" is blurring, and the new phase is defined more by capabilities and customer experience than by labels.

Crypto and digital assets: from hype to selective integration

South America has often appeared near the top of global crypto adoption rankings, driven by macroeconomic volatility, currency depreciation, and capital controls in several countries. Data from Chainalysis' 2023 Geography of Cryptocurrency Report shows that Brazil and Argentina are among the region's largest crypto markets by transaction volume, with significant retail and institutional participation.

However, the crypto story in South America is entering a more nuanced phase:

On one side, consumer-facing fintechs are integrating crypto as a feature rather than a core identity. Nubank, Mercado Pago, and several regional brokers now allow users to buy and sell major cryptocurrencies within existing apps. This "crypto-light" integration offers diversification and speculative exposure while keeping users inside regulated platforms. It also helps firms increase engagement and fee income without fully pivoting into decentralized finance.

On the other side, regulators are tightening oversight. Brazil has passed a legal framework for virtual asset service providers, overseen by the BCB and the Comissão de Valores Mobiliários (CVM), with detailed rules available on the CVM portal. Argentina's central bank and securities regulator have issued multiple warnings on unregistered crypto products, and Chile's CMF has clarified the status of certain crypto-linked instruments. The Financial Action Task Force (FATF) has also pushed for stronger AML/CFT controls on virtual asset providers, influencing national rules across the region.

The result is a more regulated, less speculative environment where crypto is increasingly treated as one asset class among many, and where institutional-grade custody, compliance, and tokenization use cases (such as on-chain receivables or trade finance) are slowly emerging. For readers interested in the intersection of digital assets and broader markets, this evolution ties closely to our crypto and stock markets coverage.

Regulation: balancing innovation, competition, and stability

Regulation is now the key determinant of how far and how fast digital finance can reshape South America's financial systems. Policymakers face a delicate balance: they want competition and inclusion, but must manage risks around consumer protection, data privacy, cyber security, and systemic stability.

Brazil remains the reference point. The BCB has pursued what it calls a "BC#" agenda-focused on competitiveness, inclusion, transparency, and education-under which Pix, Open Finance, and tighter prudential rules for fintech credit companies have been rolled out. Public documents on the Central Bank's site detail how non-bank credit fintechs are supervised as financial institutions, subject to capital and risk management requirements. This framework has allowed high growth while limiting the build-up of opaque, unregulated credit.

Chile's Fintech Law is another example of a structured approach. It creates licensing categories for crowdfunding platforms, alternative trading systems, and financial instrument advisors, and sets the stage for open finance. The CMF has emphasized proportional regulation, meaning smaller or lower-risk entities face lighter requirements, which could encourage innovation while maintaining oversight.

Elsewhere, progress is more uneven. Colombia has experimented with "regulatory sandboxes" through its Superintendencia Financiera, allowing banks and fintechs to test new models such as crypto-trading pilots under controlled conditions, as described on the regulator's innovation hub. Argentina, facing macroeconomic instability and frequent policy shifts, has seen more fragmented regulatory developments, with some measures tightening FX and crypto operations while others aim to expand digital payments and fintech participation.

Across the region, three regulatory themes are becoming central:

Interoperability mandates, pushing wallets, QR codes, and payment systems to work together rather than operate in closed silos.

Data governance and privacy, as open finance frameworks expand the volume and sensitivity of shared data, often intersecting with national data protection laws.

Prudential treatment of fintech credit, especially as non-bank lenders and BNPL providers extend credit to consumers and SMEs outside traditional banking channels.

For financial institutions and founders, tracking these shifts is no longer optional. Regulatory strategy is becoming as important as product design or user acquisition.

Inclusion, informality, and the real economy

One of the most important questions is whether digital finance is genuinely improving inclusion and productivity or simply reshuffling existing formal-sector customers among new providers. Evidence so far is mixed but trending positive.

The pandemic-era expansion of digital accounts allowed governments in Brazil, Colombia, Peru, and elsewhere to deliver emergency transfers more quickly and with less leakage than traditional cash-based schemes. Studies by organizations such as the Inter-American Development Bank (IDB), accessible via its knowledge hub, suggest that digital payments can reduce transaction costs and improve transparency in social programs.

For micro and small enterprises, particularly in retail and services, low-cost QR or app-based acceptance has opened access to electronic payments with minimal hardware investment. In Brazil, Pix has allowed street vendors and informal merchants to accept instant transfers at little or no cost, broadening their customer base and reducing reliance on cash. Similar patterns are emerging with wallet-based QR acceptance in markets like Peru and Colombia.

However, challenges remain:

A large share of the workforce in countries such as Bolivia, Peru, and Paraguay is still informal, with volatile income and limited documentation. This makes traditional credit assessment difficult, even when individuals have digital wallets. Without careful design, digital lending can become a high-cost, short-term debt trap rather than a tool for productive investment.

Digital divides persist in rural areas and among older or less-educated populations. Even where mobile coverage exists, data costs, device affordability, and digital literacy limit usage. Inclusion strategies increasingly require partnerships between fintechs, governments, and civil-society organizations, not just better apps.

There is also a risk of "over-digitization" without corresponding improvements in consumer protection. Cases of fraud, phishing, and account takeovers have increased alongside digital usage. Central banks and regulators across the region have responded with public-awareness campaigns and stronger liability rules, but enforcement and redress mechanisms are still evolving.

For readers following broader economy and employment trends, these dynamics matter because digital finance is increasingly intertwined with labor markets, social protection, and small-business growth.

Funding, profitability, and consolidation pressures

Global venture funding for fintech cooled significantly after the 2021 peak, and South America was no exception. Data from CB Insights and PitchBook indicate that Latin American fintech funding fell in 2022-2023, though the region still attracted notable deals in payments, credit, and infrastructure. The funding environment has pushed many startups to prioritize profitability and unit economics over pure user growth.

This shift is likely to drive consolidation in several ways:

Smaller, single-product fintechs may struggle to reach scale or regulatory thresholds and could be acquired by larger players seeking capabilities or customer bases. Banks may buy technology providers or niche fintechs to modernize faster than in-house efforts would allow. Some cross-border mergers or partnerships may emerge as firms try to build regional, not just national, footprints.

At the same time, public markets are sending mixed signals. Nubank's listing on the New York Stock Exchange, Mercado Libre's long-standing presence as a Latin American tech bellwether, and the performance of listed Brazilian payment processors (such as PagSeguro and StoneCo) provide benchmarks for investors assessing the sustainability of digital finance business models in the region. These companies' quarterly reports, available through the NYSE and the firms' investor-relations sites, show how credit quality, funding costs, and regulatory changes are affecting profitability.

For founders and investors, the new phase is less about "greenfield" disruption and more about execution in a more crowded, regulated, and macroeconomically uncertain environment. That makes strategic discipline and risk management more central than in the exuberant pre-2022 funding climate.

Cross-border ambitions and regional fragmentation

While "Latin America" is often discussed as a single market, financial regulation, currency regimes, and consumer behavior vary widely across South America. This fragmentation complicates the regional scaling ambitions of fintechs and digital banks.

Brazil's size and regulatory complexity make it a market unto itself. Successful Brazilian players have begun expanding to Mexico and Colombia, but replicating Pix-like infrastructure or open finance frameworks elsewhere depends on local central banks and governments. Spanish-speaking South American markets share some linguistic and cultural affinities, yet differences in tax regimes, FX controls, and licensing rules can significantly alter business cases.

Cross-border payments remain a pain point. Remittances within South America and between the region and destinations like the United States or Europe are still relatively costly and slow, despite digital wallets and specialized remittance fintechs. Initiatives such as the Bank for International Settlements (BIS) Innovation Hub's cross-border projects, documented on the BIS website, aim to test new models for linking fast-payment systems across countries, but practical implementation is still at an early stage.

In the meantime, some firms are using multi-entity structures, partnerships with local banks, or card-network rails to offer quasi-cross-border solutions. Yet regulatory arbitrage risks and compliance costs can be significant. The next phase of digital finance in South America will likely include more experimentation with regional interoperability-both at the public-infrastructure level and via private-sector networks.

What the new phase means for businesses and investors

For corporates, startups, and investors looking at South America's digital finance market, several strategic implications stand out.

First, infrastructure and regulation are now central competitive battlegrounds. Firms that can best leverage real-time payment rails, open finance APIs, and interoperable standards will have an edge in cost, speed, and customer experience. Staying ahead requires close monitoring of central bank policies, regulatory consultations, and technical-standard updates, not just consumer trends.

Second, partnerships are becoming more important than pure disruption narratives. Banks, fintechs, Big Tech platforms, and even telecoms are forming alliances to combine licenses, balance sheets, data, distribution, and technology. The ability to structure, govern, and manage these partnerships will be a key differentiator.

Third, risk management and trust are emerging as long-term moats. As more consumers and businesses move critical financial activity online, tolerance for outages, fraud, or opaque terms is falling. Firms that invest in robust cyber security, transparent pricing, and effective customer support may build durable reputational advantages, especially in markets where institutional trust has historically been fragile.

Fourth, macro volatility remains a defining feature. Inflation spikes, currency swings, and political transitions can quickly alter demand for credit, savings, and payment products. Business models that rely on cheap external funding or aggressive FX assumptions may prove fragile; those built around flexibility, local funding, and diversified revenue are more likely to endure.

For readers tracking these shifts from a broader business and global perspective, South America offers a powerful case study of how digital finance can transform emerging markets-provided that innovation, regulation, and inclusion advance together.

As the region enters this new phase, the winners are likely to be those who understand that digital finance is no longer a niche sector. It is becoming part of the core infrastructure of South American economies, shaping how people are paid, how they save and borrow, and how companies of all sizes operate in an increasingly interconnected financial system.

How Interest Rate Shifts Change Corporate Strategy

Last updated by Editorial team at bizfactsdaily.com on Saturday 24 October 2026
Article Image for How Interest Rate Shifts Change Corporate Strategy

How Interest Rate Shifts Reshape Corporate Strategy

When central banks move interest rates, the immediate headlines tend to focus on mortgages, consumer loans, and stock indices. Inside companies, though, those same shifts trigger a much broader strategic rethink: which projects to fund, how aggressively to expand, whether to buy competitors, how much inventory to hold, and even how to price products.

This article looks at how changing interest rates filter through corporate decision-making, from capital structure and investment to M&A, employment, and innovation. The emphasis is on practical implications for businesses operating in a world of more volatile monetary policy.

From "free money" to higher yields: why rates matter so much

For more than a decade after the global financial crisis, many advanced economies operated in a regime of near-zero or even negative policy rates. That era ended when inflation surged after the pandemic. Central banks including the U.S. Federal Reserve, European Central Bank, and Bank of England embarked on the fastest tightening cycle in decades, lifting policy rates by several percentage points in a short period.

Policy rates such as the federal funds rate directly influence short-term borrowing costs and indirectly affect longer-term yields through expectations and central bank balance sheets. Corporate borrowing costs-on bank loans, bonds, and commercial paper-are typically priced as a spread over these benchmarks. When central banks raise rates, yields on government bonds rise, investors demand higher returns on corporate debt, and the weighted average cost of capital (WACC) for firms increases.

Because corporate strategy ultimately revolves around allocating capital under uncertainty, any change in the cost of that capital forces companies to revisit their assumptions. Projects that looked attractive in a low-rate environment may no longer clear the hurdle rate; conversely, when rates fall, previously marginal investments can suddenly become viable. This basic mechanism underpins many of the strategic shifts discussed below.

For readers interested in broader macro implications, our coverage of global economic trends and banking explores how monetary policy interacts with financial markets and growth.

Capital structure: rethinking debt, equity, and leverage

One of the most immediate strategic responses to interest rate shifts concerns how companies finance themselves. During periods of low rates, many firms increased leverage, locking in cheap long-term debt and using proceeds to fund expansion, acquisitions, or shareholder returns. When rates rise, the calculus changes.

In a high-rate environment, rolling over maturing debt becomes more expensive. Companies with large volumes of floating-rate liabilities, such as syndicated loans tied to benchmarks like SOFR or Euribor, see interest expense rise quickly as reference rates reset. Firms with fixed-rate bonds are partially shielded, but face higher costs when they eventually refinance. Ratings agencies such as S&P Global Ratings and Moody's often flag interest coverage ratios and refinancing walls as key risks when rates are elevated.

Strategically, this tends to push companies to:

Reduce leverage targets and prioritize debt repayment over aggressive expansion.

Extend maturities when markets are receptive, even at slightly higher coupons, to avoid bunching of refinancing risk.

Shift toward equity financing or retained earnings, especially for growth investments.

Increase use of interest rate hedging instruments such as swaps and caps to stabilize cash flows.

When rates fall, the pattern reverses. Companies may opportunistically refinance higher-cost debt, increase leverage to fund share buybacks or special dividends, and pursue larger-scale acquisitions. The Bank for International Settlements (BIS) has documented how low-rate environments encourage corporate leverage and risk-taking, which can amplify vulnerabilities when conditions tighten.

Strategic finance decisions around capital structure intersect with broader business choices. Highly leveraged firms may become more conservative on investment and hiring, while companies with strong balance sheets can exploit dislocations to gain market share or acquire distressed competitors.

Investment decisions: hurdle rates, project mix, and timing

Interest rates feed directly into capital budgeting through the discount rate used to evaluate projects. Most firms rely on metrics such as net present value (NPV), internal rate of return (IRR), and payback period to prioritize investments. When the risk-free rate rises, the WACC increases, raising the minimum acceptable return for new projects.

This shift tends to produce several strategic effects:

First, the project mix changes. Long-duration projects-such as large infrastructure builds, new manufacturing plants, or ambitious R&D programs-are more sensitive to the discount rate because their cash flows are further in the future. As rates rise, these projects' NPVs fall more sharply than shorter-term initiatives. Firms may pivot toward incremental, quicker-payback investments, such as process improvements, automation upgrades, or targeted digital initiatives.

Second, geographic choices are affected. Multinationals compare after-tax returns across countries, adjusting for local interest rates, inflation, and currency risk. When some central banks hike more aggressively than others, relative financing conditions diverge. For example, a firm headquartered in the United States might find it more attractive to fund projects in markets where local borrowing costs remain lower, provided currency and political risks are manageable.

Third, timing becomes a strategic lever. If management expects rates to decline in the near future, it may defer certain capital-intensive projects to benefit from cheaper financing later. Conversely, when rates are expected to rise further, companies sometimes accelerate investments and borrowing to lock in current terms.

For executives grappling with these choices, the interplay between macro forecasts and company-specific strategy is critical. Central bank communications, such as the Fed's Summary of Economic Projections or the ECB's monetary policy statements, provide signals about likely rate paths but are inherently uncertain. Building flexibility into project plans-through modular investments, staged funding, or option-like structures-can help firms adapt as conditions evolve.

Readers seeking more on how financial markets price these expectations can explore our coverage of stock markets and global developments.

M&A and corporate dealmaking: cycles driven by the cost of money

Mergers and acquisitions are especially sensitive to the rate environment, because deal values often rely on leverage and discounted cash flow models. Periods of low interest rates typically correspond with busy M&A markets, as cheap debt makes leveraged buyouts and large strategic deals more feasible. Private equity firms, in particular, rely on access to affordable leverage to achieve target returns.

When central banks tighten, several things change in the deal landscape:

Financing becomes more expensive and sometimes scarcer. Banks and credit funds may pull back from riskier leveraged loans, as seen during the tightening cycles documented by PitchBook and other industry sources. Deals that assumed optimistic financing conditions can stall or be repriced.

Valuations compress. Higher discount rates reduce the present value of target companies' projected cash flows, particularly for high-growth or cash-flow-light businesses. Public market multiples often fall first, which then feeds into private deal negotiations. Strategic buyers may see an opportunity to acquire assets at lower prices, but only if their own balance sheets and share prices remain resilient.

Deal structures become more conservative. Earn-outs, contingent consideration, and seller financing can bridge valuation gaps when uncertainty is high. Buyers may favor bolt-on acquisitions that are easier to integrate and finance rather than transformative mega-deals.

Conversely, when rates fall or stabilize after a tightening cycle, pent-up M&A demand can emerge. Corporates that delayed deals may re-enter the market, and private equity firms sitting on "dry powder" can become more active. Understanding where the interest rate cycle sits is therefore central to long-term acquisition strategies, especially in sectors like technology, healthcare, and infrastructure where consolidation is ongoing.

For founders and executives considering exits or acquisitions, it is important to distinguish between cyclical valuation effects driven by rates and structural changes in industry dynamics. Our founders and business sections frequently discuss how timing and macro conditions influence deal outcomes.

Working capital, inventory, and pricing: the operational ripple effects

Interest rates also affect day-to-day operational decisions that might not be labeled "strategic" but collectively shape a firm's resilience and profitability. The cost of carrying working capital-inventory, receivables, and cash buffers-rises with interest rates, because funds tied up in operations could otherwise earn higher returns in risk-free instruments.

In a higher-rate environment, companies typically re-examine:

Inventory policies. Holding excess stock becomes more expensive when financing costs are high. Firms may push for leaner inventories, faster turnover, and improved demand forecasting. However, after pandemic-era supply chain disruptions, many businesses are reluctant to return fully to "just-in-time" models, creating a tension between resilience and capital efficiency.

Customer credit terms. Extending generous payment terms effectively turns suppliers into lenders to their customers. When rates rise, the opportunity cost of financing receivables increases. Companies may tighten credit policies, offer early-payment discounts, or use supply chain finance programs to optimize cash flow. Organizations such as the International Chamber of Commerce (ICC) and World Trade Organization (WTO) provide guidance and data on trade finance trends that often reflect these shifts.

Supplier negotiations. Firms facing higher borrowing costs may seek longer payment terms from their own suppliers, which can push stress down the supply chain, especially to smaller businesses with limited access to credit. Strategic procurement must balance cost, reliability, and the financial health of key partners.

Product pricing and contracts. Where possible, companies may build interest-rate-linked clauses into long-term contracts or adjust pricing to reflect higher financing costs. In sectors like commercial real estate, infrastructure, and utilities, rate pass-through mechanisms are often embedded in regulatory or contractual frameworks. In more competitive markets, the ability to raise prices without losing customers depends on brand strength and differentiation.

These operational adjustments connect directly to broader themes in employment and marketing, as companies decide where to cut costs, how to position value to customers, and which markets to prioritize.

Employment, wages, and talent strategy under shifting rates

Interest rate policy is closely linked to labor market conditions. Central banks often raise rates to cool inflation, which can involve slowing demand and moderating wage growth. For companies, this environment creates a complex set of trade-offs in workforce strategy.

When rates rise and growth slows, some firms respond with hiring freezes, reduced overtime, or layoffs, particularly in interest-sensitive sectors such as construction, real estate, and consumer durables. The tech sector's wave of layoffs following the end of ultra-cheap money illustrates how business models built on rapid, subsidized growth can become less sustainable when financing costs rise and investors demand profitability.

At the same time, structural labor shortages in certain fields-such as software engineering, healthcare, and advanced manufacturing-mean that even in a higher-rate environment, competition for critical talent remains intense. Companies may choose to protect or even increase investment in key skills while cutting elsewhere.

Strategic HR decisions influenced by rates include:

Balancing permanent staff versus contractors or gig workers to maintain flexibility.

Investing in automation and AI to reduce long-term labor intensity.

Re-evaluating geographic footprints, including offshoring and nearshoring, to manage wage and financing costs together.

Institutions like the OECD and International Labour Organization (ILO) regularly publish data on how monetary policy and macro conditions affect employment, which many corporate strategy teams integrate into their planning.

For organizations exploring how automation and AI fit into this picture, our coverage of artificial intelligence and technology examines the interplay between digital transformation, productivity, and labor markets.

Innovation, R&D, and technology adoption: rate sensitivity with a twist

Innovation spending is often described as discretionary, but its relationship with interest rates is nuanced. On one hand, higher rates make long-term, uncertain-payoff projects harder to justify in traditional NPV terms. On the other, disruptive innovation can be a key route to maintaining margins and competitiveness when growth slows.

Historically, low-rate environments have supported high valuations for growth and technology companies, encouraging heavy investment in R&D and speculative ventures such as early-stage biotech or frontier tech. Venture capital funding surged during periods of easy money, as documented by organizations such as the National Venture Capital Association (NVCA) and Invest Europe. When rates rise, risk capital becomes scarcer, valuations fall, and early-stage companies must adjust burn rates and funding expectations.

For established corporates, the strategic response varies:

Some cut back on exploratory R&D and focus on near-term, incremental innovation that supports cost reduction or product line extensions. This can protect margins in the short run but risks eroding long-term competitiveness.

Others double down on transformative technologies-such as AI, automation, and advanced analytics-to structurally lower operating costs and open new revenue streams. For example, banks facing higher funding costs may accelerate digital transformation to reduce branch networks and manual processing.

In sectors tied to sustainability and the energy transition, interest rates interact with policy incentives. Capital-intensive projects like renewable energy, grid upgrades, and electric vehicle infrastructure are sensitive to financing costs, but also benefit from subsidies, tax credits, and regulatory mandates. Agencies such as the International Energy Agency (IEA) provide analysis on how financing conditions affect clean energy investment. Our sustainable business and innovation coverage frequently explores these dynamics.

Ultimately, the firms that manage to maintain a disciplined but forward-looking innovation agenda-aligning R&D portfolios with changing capital costs and strategic priorities-tend to emerge stronger from rate cycles.

Sector differences: who feels rate shifts the most?

Not all industries experience interest rate changes in the same way. The sensitivity depends on leverage levels, asset intensity, regulatory frameworks, and demand patterns.

Highly interest-sensitive sectors include:

Real estate and construction, where project viability and buyer demand are closely tied to mortgage and development financing costs.

Utilities and infrastructure, which rely on large upfront capital outlays and regulated returns often benchmarked to interest rates.

Banks and other financial institutions, whose net interest margins and asset valuations are directly affected by rate spreads and yield curve shape. The Bank for International Settlements and central bank financial stability reports frequently analyze these effects.

Moderately sensitive sectors include:

Automotive and durable goods, where consumer financing plays a major role in purchasing decisions.

Capital goods and industrials, which depend on corporate investment cycles.

Less directly sensitive, though still affected, are:

Consumer staples and certain services, where demand is more stable but financing costs and wage pressures still matter.

Digital and software businesses with strong cash generation and low capital intensity, which can be relatively insulated from higher rates, though not from valuation compression in public markets.

For investors and corporate planners, understanding where their sector sits on this spectrum helps calibrate strategy-whether to lean into expansion, conserve cash, or reposition the business model.

Risk management and scenario planning: from spreadsheets to strategy

Interest rate volatility highlights the importance of robust risk management and scenario planning. Many companies treat interest expense as a relatively static line item; in a more turbulent environment, it becomes a strategic variable.

Leading practices include:

Developing multiple macro scenarios. Strategy and finance teams often build base, optimistic, and pessimistic rate paths informed by central bank guidance, market-implied expectations (such as yield curves and futures), and independent research from institutions like the IMF or World Bank. Each scenario feeds into forecasts for revenue, costs, and capital needs.

Stress-testing balance sheets. Firms simulate the impact of rate shocks on interest coverage, covenant headroom, liquidity, and refinancing risk. This is especially important for companies with significant short-term or floating-rate debt. Regulators routinely stress-test banks; non-financial corporates increasingly adopt similar disciplines.

Aligning hedging with strategy. Derivatives can smooth interest costs, but poorly aligned hedges can create their own risks. Treasury policies need to reflect the firm's risk appetite, investment horizon, and capital structure targets. Industry bodies such as the Association for Financial Professionals (AFP) offer guidance on best practices in corporate risk management.

Integrating finance and strategy. Perhaps most importantly, interest rate assumptions should not live only in the treasury function. Product strategy, geographic expansion, M&A, and technology investment all depend on the cost of capital. Regular communication between CFOs, strategy leaders, and business units is essential.

Readers interested in the broader financial market implications of these risk practices can find additional context in our investment and news coverage.

Strategic playbook: how companies can adapt across the rate cycle

While every business is different, several broad principles help firms navigate shifting interest rate regimes:

First, maintain balance sheet flexibility. Excessive leverage during low-rate periods can become a constraint when conditions tighten. Preserving some capacity-through conservative debt levels, diversified funding sources, and manageable maturities-gives management options to invest or acquire when competitors are forced to retrench.

Second, design investment portfolios with optionality. Instead of committing solely to large, irreversible projects, firms can structure initiatives in phases, with clear decision gates tied to market conditions and performance. This approach reduces the risk of being locked into uneconomic projects if financing costs rise unexpectedly.

Third, align growth strategies with funding realities. Business models that require continuous external financing, such as aggressive land banking in real estate or highly cash-burning tech ventures, are far more vulnerable when rates rise and investor sentiment shifts. Adjusting growth expectations, pricing strategies, and cost structures to be viable under more normalized rates is critical.

Fourth, use technology and process improvements as structural responses. While interest rates are cyclical, productivity gains from automation, AI, and process redesign can permanently improve margins and resilience. Strategic investments in these areas can pay off across different rate environments, even if the pace and scale of spending must be tuned to financing costs.

Finally, communicate clearly with investors, employees, and partners. Explaining how the company's strategy accounts for changing rates-what trade-offs are being made, where the firm is taking risk, and how it is protecting its financial health-helps build trust and reduce uncertainty.

Interest rate shifts are not merely a backdrop to corporate life; they are a central force reshaping how businesses allocate capital, compete, and grow. The companies that treat monetary conditions as a core strategic variable-rather than an external annoyance-are better positioned to navigate volatility, seize opportunities, and build durable value through the cycle.

Crypto Market Structure Evolves Around Institutional Access

Last updated by Editorial team at bizfactsdaily.com on Friday 23 October 2026
Article Image for Crypto Market Structure Evolves Around Institutional Access

How Crypto Market Structure Is Being Rebuilt Around Institutional Access

The last five years have quietly turned crypto from a retail-driven, offshore, lightly regulated market into something that increasingly resembles traditional finance. Trading is shifting onshore, liquidity is concentrating on a smaller set of large venues, and the products, plumbing, and rules are being redesigned with one customer in mind: institutions. Understanding how this new market structure is emerging is critical for banks, asset managers, corporates, and sophisticated investors deciding whether and how to participate.

This page looks at the main building blocks of that shift: regulation and jurisdiction, the rise of institutional trading venues and custodians, the changing role of market makers and derivatives, and what all of this means for liquidity, pricing, and risk.

From retail and offshore to regulated and onshore

For most of the 2010s, crypto trading was dominated by retail investors on offshore exchanges, often offering high leverage, minimal KYC, and little transparency. Platforms such as BitMEX, Binance, and OKX set the tone for market microstructure: order-book spot and perpetual futures, 24/7 trading, and a fragmented global venue landscape with weak regulatory harmonization.

That profile has changed sharply since 2020. The entry of listed companies like MicroStrategy and Tesla into bitcoin, the emergence of crypto hedge funds and arbitrage firms, and the launch of institutional products such as the CME's cash-settled bitcoin futures all began to pull liquidity into more traditional channels. The collapse of FTX in November 2022 then accelerated a migration away from opaque offshore venues toward more regulated markets.

Regulators have responded with clearer frameworks. In the European Union, the Markets in Crypto-Assets Regulation (MiCA) is creating a passportable regime for crypto-asset service providers, including trading platforms and custodians. In the United States, the Securities and Exchange Commission (SEC) and Commodity Futures Trading Commission (CFTC) have stepped up enforcement, while the approval of spot bitcoin exchange-traded products in early 2024 and 2025 signaled grudging acceptance of crypto as an investable asset class, at least for bitcoin.

As a result, the center of gravity for institutional flows is moving toward jurisdictions with more predictable rules, notably the U.S., EU, UK, Singapore, and Hong Kong. That shift is reshaping which intermediaries matter, what products are offered, and how liquidity is accessed.

For readers tracking broader digital-asset regulation and macro conditions, our coverage of global business trends and economy developments provides additional context.

The rise of institutional trading venues

Institutional access demands more than a new legal framework. It requires venues that look and feel like traditional exchanges and broker-dealers: strong compliance, robust market surveillance, high uptime, and integration with existing trading infrastructure.

Several models are emerging.

Regulated exchanges and ATS-style platforms

In the U.S. and Europe, a number of firms are building crypto trading venues that mimic equities or FX market structure. Platforms such as CME Group's bitcoin and ether futures markets, Cboe Digital, and institutional arms of major exchanges offer central limit order books, regulated clearing, and connectivity through standard APIs and FIX gateways. CME's bitcoin futures, for example, are cleared alongside other derivatives and fall under the same regulatory umbrella as traditional futures products, which has helped them become a benchmark for institutional price discovery. The CME publishes contract specs and volume data on its official bitcoin futures page, underscoring their growing role.

In parallel, several crypto-native firms have sought licenses as multilateral trading facilities or alternative trading systems (ATS) to serve professional investors. These platforms often focus on spot trading but may also offer derivatives, lending, and staking services where regulations permit. Their pitch is straightforward: the execution experience of a crypto exchange, with the compliance posture of a regulated market.

For institutional readers interested in where crypto fits into broader investment strategy or stock markets infrastructure, the convergence with traditional venues is a key theme to watch.

Prime brokers and agency execution

Another major change is the emergence of crypto prime brokerage. In the early market, institutions had to open and manage multiple exchange accounts, move collateral manually, and handle counterparty and operational risk themselves. Today, specialized crypto prime brokers and agency execution firms aggregate liquidity from many venues, manage collateral centrally, and provide services such as margin financing, rehypothecation management, and cross-venue netting.

This mirrors the structure of FX and equity markets, where buy-side firms rarely connect directly to every exchange. Instead, they route orders through a handful of prime brokers and electronic liquidity providers. Crypto is moving in the same direction, which both simplifies access and concentrates risk in a smaller set of intermediaries.

The International Swaps and Derivatives Association (ISDA) has even published digital-asset derivatives definitions to standardize documentation, making it easier for banks and hedge funds to integrate these products into existing risk and legal frameworks.

Institutional-grade custody and settlement

For many large investors, the single biggest barrier to entering crypto was not price volatility but safekeeping. Holding private keys on a USB drive is incompatible with institutional governance, audit, and insurance requirements. The evolution of custody is therefore central to the new market structure.

Segregated, insured, and regulated custody

Specialist custodians now offer multi-layer security models combining hardware security modules, multi-party computation (MPC), and geographically distributed key shards. Many seek regulation as qualified custodians or trust companies in jurisdictions such as New York, Wyoming, Switzerland, and Singapore. Some traditional custodians, including BNY Mellon and Fidelity, have launched or expanded digital-asset custody services, using their existing relationships and compliance apparatus to attract conservative institutions.

Regulators have also weighed in. The Bank for International Settlements (BIS) and national supervisors have issued guidance on how banks should treat crypto exposures and custody risk for capital purposes. In the EU, MiCA defines rules for "crypto-asset service providers," including custodians, while the UK's Financial Conduct Authority (FCA) has set expectations around safeguarding and operational resilience. These frameworks are gradually reducing the perceived legal and operational risk of institutional crypto custody.

New settlement models: from pre-funding to post-trade netting

On retail-oriented exchanges, users typically pre-fund their accounts and trade against the exchange's omnibus wallet. That model is capital-intensive and creates credit exposure to the exchange itself. Institutions are pushing for something closer to traditional securities settlement: delivery-versus-payment (DvP), post-trade netting, and central clearing.

Several initiatives are experimenting with on-chain or near-real-time settlement between custodians and exchanges. In some models, assets remain at a regulated custodian and are pledged to a trading venue via on-chain smart contracts or off-chain messaging, reducing the need to move coins for every trade. Others explore central counterparty clearing for crypto derivatives, similar to listed futures.

The broader push for more efficient and safer settlement parallels innovation elsewhere in banking and technology, particularly experiments with tokenized securities and instant payment systems.

Derivatives, leverage, and the institutional liquidity stack

The shape of crypto liquidity is changing as derivatives markets mature and institutional flows grow. Historically, perpetual swaps on offshore exchanges dominated both volume and price discovery. While those instruments remain important, regulated futures and options markets are taking a larger share.

Futures and options as institutional gateways

CME's bitcoin and ether futures and options, as well as listed products on venues like Eurex and some Asian exchanges, offer exposure via established clearinghouses and brokerage channels. For many asset managers and corporates, these are the only acceptable way to gain crypto exposure because they avoid direct token custody and fit existing mandates. Data from CME and analytics firms such as The Block and Kaiko show that open interest and institutional participation in regulated futures have trended upward, especially around major macro events and ETF launches.

Options markets are also deepening, with platforms like Deribit still dominating offshore but regulated options slowly gaining traction. For institutional portfolios, options provide tools for hedging, yield enhancement, and volatility trading, making crypto more manageable as a risk budget component.

Structured products and yield strategies

In parallel, banks and structured-product issuers have begun offering notes, certificates, and total-return swaps linked to bitcoin and ether, often delta-hedged in the background via futures and spot markets. These products resemble equity-linked notes or FX structured products and appeal to wealth-management clients who prefer familiar wrappers.

On the crypto-native side, decentralized finance (DeFi) protocols and centralized lenders once offered high yields through lending, staking, and liquidity provision. After the failures of Celsius, BlockFi, and others, institutions have become more cautious, favoring transparent, over-collateralized lending platforms or on-chain strategies with clearer risk profiles. The Bank for International Settlements has documented the systemic risks seen in 2022's crypto credit cycle in its reports on DeFi and stablecoins, helping shape institutional risk frameworks.

Readers following DeFi, tokenization, and the intersection of crypto with innovation and artificial intelligence can expect these derivatives and yield products to be key building blocks in more complex strategies.

ETFs and the transformation of access channels

Perhaps the single most visible change in institutional access has been the approval of spot bitcoin exchange-traded funds in major markets. These vehicles have altered both how institutions access crypto and how liquidity flows back into the underlying markets.

Spot bitcoin ETFs as institutional on-ramps

In the U.S., the SEC's January 2024 approval of multiple spot bitcoin ETFs-sponsored by firms such as BlackRock, Fidelity, and Invesco-created a new, regulated channel for exposure. The SEC's approval orders and subsequent filings detail the surveillance-sharing agreements and market-manipulation safeguards the regulator demanded, signaling a more mature approach to crypto market oversight.

These ETFs trade on traditional stock exchanges and settle through established securities infrastructure, allowing pension funds, RIAs, and corporate treasuries to buy bitcoin exposure without touching a crypto exchange or wallet. Flows into these products, tracked by firms like CoinShares and Bloomberg Intelligence, quickly became a significant driver of underlying bitcoin spot demand.

Other jurisdictions, including Canada, Brazil, and several European countries, had already listed spot bitcoin and ether ETPs, but the U.S. market's depth and global signaling effect have been decisive for many institutions.

Feedback loops between ETFs, spot, and derivatives

The growth of ETFs has changed market structure in subtler ways. Authorized participants and market makers arbitrage price differences between ETF shares, CME futures, and spot markets across exchanges. This creates a complex feedback loop: ETF flows influence futures basis and funding rates, which in turn shape the incentives for arbitrage and hedging.

For example, when ETF inflows are strong, ETF market makers may buy spot bitcoin on multiple exchanges and hedge via futures, tightening spreads and contributing to price discovery on regulated venues. Conversely, during outflows, selling pressure can propagate from ETFs to futures and then into spot order books. This dynamic is similar to what happens in equity index ETFs but layered on top of a still-fragmented global crypto market.

Market makers, HFT, and the professionalization of liquidity

As institutions demand tighter spreads and deeper books, the role of professional market makers and high-frequency trading (HFT) firms has expanded. Many firms that cut their teeth in equities, FX, and commodities now run substantial crypto operations, applying familiar quantitative strategies to a 24/7, multi-venue environment.

Consolidation of liquidity providers

Crypto market making used to be dominated by a handful of native firms that grew alongside the exchanges. Since 2020, large electronic trading firms and some bank-affiliated dealers have increased their footprint, often focusing on the most liquid instruments: BTC and ETH spot, major stablecoins, and regulated futures. They bring sophisticated risk-management systems, co-location, and low-latency infrastructure that can arbitrage price discrepancies across dozens of venues and instruments.

This professionalization narrows bid-ask spreads and supports larger block trades, which is essential for institutional participation. However, it also concentrates liquidity provision in fewer hands, raising questions about resilience if a major player withdraws, as seen when some firms scaled back after the FTX collapse.

Algorithmic execution and dark liquidity

Institutions typically do not want to cross the spread with large market orders on public order books, especially in an asset as volatile as bitcoin. Instead, they use algorithmic execution strategies-VWAP, TWAP, iceberg orders-or tap into request-for-quote (RFQ) systems and dark pools that match block trades off-exchange.

Several institutional venues now offer RFQ platforms where buy-side firms can solicit quotes from multiple market makers simultaneously, similar to corporate bond or FX trading. This reduces market impact and information leakage, aligning crypto execution with established best practices in other asset classes.

The evolution of execution tools is one of the clearest examples of crypto adapting to the needs of professional traders rather than the other way around.

DeFi, tokenization, and the institutional perimeter

While much of the new market structure is being built within traditional regulatory perimeters, decentralized finance and tokenization are creating parallel rails that institutions are cautiously exploring.

DeFi as an execution and liquidity venue

Protocols like Uniswap, Curve, and on-chain lending pools once catered mainly to retail and crypto-native funds. Over time, some institutions have begun to interact with DeFi, often through whitelisted or permissioned pools that enforce KYC/AML requirements. Projects such as Aave's institutional markets and on-chain credit facilities backed by real-world assets aim to blend DeFi's transparency and programmability with compliance.

The Financial Stability Board and BIS have highlighted DeFi's potential and risks in joint reports on crypto-asset markets, underscoring issues like smart-contract vulnerabilities, oracle risk, and governance concentration. For now, most large institutions treat DeFi as an experimental adjunct to, not a replacement for, centralized venues.

Readers interested in the broader crypto landscape can find more background in our dedicated crypto and technology coverage.

Tokenized assets and the blurring of boundaries

Separately, banks and market-infrastructure providers are piloting tokenized versions of traditional assets-bonds, money-market funds, repo, and even bank deposits-on both public and permissioned blockchains. The Monetary Authority of Singapore's Project Guardian and experiments by firms such as JPMorgan, HSBC, and UBS illustrate how tokenization could enable intraday repo, programmable collateral, and atomic settlement.

While not "crypto" in the retail sense, these initiatives share infrastructure and sometimes liquidity with crypto markets. An institutional desk trading tokenized treasuries on a permissioned chain may also be hedging bitcoin futures on CME or providing liquidity in stablecoin pairs. Over time, this could create a more integrated digital-asset ecosystem in which crypto, tokenized securities, and even central bank digital currencies interact.

Implications for market structure, risk, and strategy

The reorientation of crypto around institutional access is not just a story about bigger tickets and more regulation. It is altering the fundamental mechanics of price discovery, liquidity, and systemic risk.

For business leaders and investors, several themes stand out:

First, liquidity is becoming more bifurcated. The most institutionally accepted assets-primarily bitcoin and ether-are seeing deeper, more stable liquidity on regulated venues, ETFs, and major exchanges. Long-tail tokens remain largely in the legacy, retail-dominated ecosystem, with thinner books and higher volatility. This split affects everything from index construction to risk budgeting and should inform how firms treat different parts of the crypto universe.

Second, counterparty and operational risk are being reshuffled rather than eliminated. Instead of dozens of offshore exchanges, risk is concentrating in a smaller set of regulated custodians, prime brokers, and market makers. These entities are more supervised and capitalized, but their interconnectedness-via rehypothecation, derivatives, and cross-margining-creates new potential fault lines, akin to those seen in traditional finance.

Third, regulatory fragmentation remains a structural challenge. While MiCA, SEC enforcement, and guidance from bodies like the Financial Action Task Force (FATF) are bringing some order, definitions of what constitutes a security, a commodity, or a payment token still vary widely. Institutions operating across regions must navigate a patchwork of rules, influencing where they locate trading entities and how they structure products.

Finally, the competitive landscape is in flux. Traditional exchanges, banks, fintechs, and crypto-native firms are all vying to become the primary gateway for institutional crypto flows. Some will focus on execution and liquidity, others on custody and settlement, and others on structuring and distribution. The winners are likely to be those that can combine regulatory credibility, technological robustness, and deep integration with existing financial infrastructure.

For organizations evaluating their own strategy, the key question is no longer whether crypto is "legitimate," but where along this emerging value chain they want to sit-and how they will manage the distinct market-structure risks that come with it.

As crypto continues to integrate with global finance, its market structure will increasingly resemble other asset classes, even as 24/7 trading, on-chain settlement, and programmable assets introduce new dynamics. Institutions that understand both the familiar and the novel elements of this evolving system will be better placed to navigate the next phase of digital-asset innovation.